The MeAgain Index is a quarterly ranking of the leading GLP-1 meds, as well as top consumer brands and trending products serving GLP-1 users. Our proprietary methodology combines real-world behavioral data from hundreds of thousands of members on the MeAgain platform with signals from across the wider GLP-1 ecosystem, including clinical trial data, research publications, product launches, third-party reported data, social media trends and emerging AI discovery channels.

Period
Jul 1 – Sep 30, 2026
Published
October 2026
Based on
Hundreds of thousands of MeAgain members
Methodology

Medicare Bridge Launches, and Fall Flavors Arrive

Medicare's $50 GLP-1 Bridge kicked off in July, and seniors didn't hesitate to take full advantage. Familiar snack favorites also came back this quarter as Fairlife's vanilla shake tops the products, and pumpkin spice and other fall flavors arrived early.

Leading GLP-1 Meds

Q3 2026

The leading GLP-1 meds are evaluated across pricing, insurance coverage, adoption, adherence, real-world weight loss outcomes, quality-of-life improvements, and new research.

  1. 01ZepboundNo change
  2. 02MounjaroNo change
  3. 03Wegovy1 place up
  4. 04Compounded tirzepatide†1 place down
  5. 05Wegovy PillNo change
  1. 06Retatrutide*1 place up
  2. 07Ozempic1 place down
  3. 08Compounded semaglutide†No change
  4. 09FoundayoNo change
  5. 10Ozempic pillNo change

†Compounded versions are prepared by pharmacies and are not FDA-approved.

*Retatrutide is an investigational medicine that is not FDA-approved. Lilly plans to file for approval in early 2027; it has no brand name yet. Its place on the list is not a recommendation.

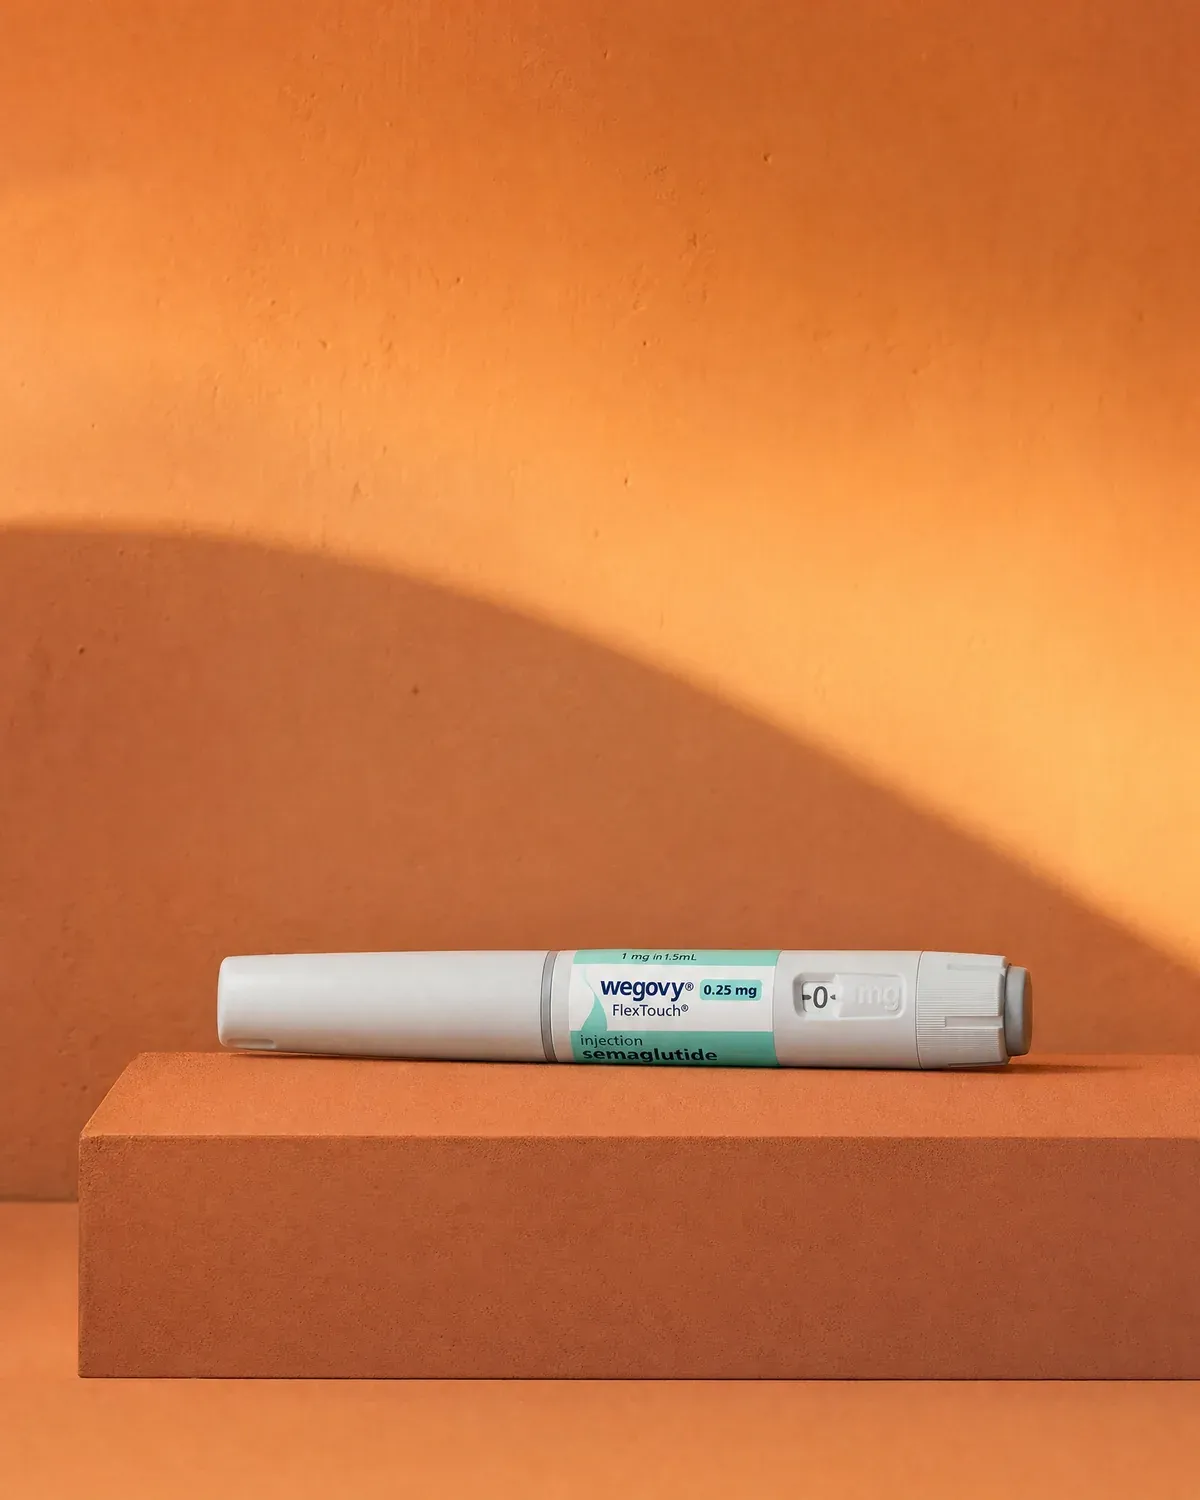
The Wegovy pen

Zepbound holds the top spot on the MeAgain Index as the most used GLP-1 on the platform and as Lilly pushed new research against Novo's newest Wegovy HD, saying Zepbound's top dose was associated with 4.5 percentage points more weight loss than Wegovy HD. A Lilly-funded study also found that adults 55+ on Zepbound had lower health care costs than similar adults who were not. Insurers may well take note of this as they decide what to cover heading into 2027. Zepbound growth also remained strong, as Lilly noted US sales rose 48% in the third quarter.

A MeAgain survey in August revealed another lead for Zepbound. Its users were the most likely to report that it is working better than they had hoped, far ahead of anyone on a non-Lilly medicine. Out of over 10,000 members, 19% of those on Zepbound said so, compared with 12% on Wegovy injections and only 8% on the Wegovy Pill.

Despite these survey results, Wegovy finally breaks into the top three meds on the MeAgain Index, moving up one place. A big change for Novo this quarter was Medicare's temporary GLP-1 Bridge, which began offering Wegovy to eligible seniors for $50 a month on July 1st, with the same coverage applying to the Wegovy Pill (which holds onto fifth).

Compounded tirzepatide slips one place to fourth. Things have not gotten any easier for compounded GLP-1s, with an appeals court upholding the end of the tirzepatide shortage in August. Even so, they still have a big following, and a Gallup survey published in July found that 18% of Americans taking a GLP-1 for weight loss use a compounded version. From what we see on the MeAgain platform, we would not be surprised if the real number is even higher than Gallup's estimate.
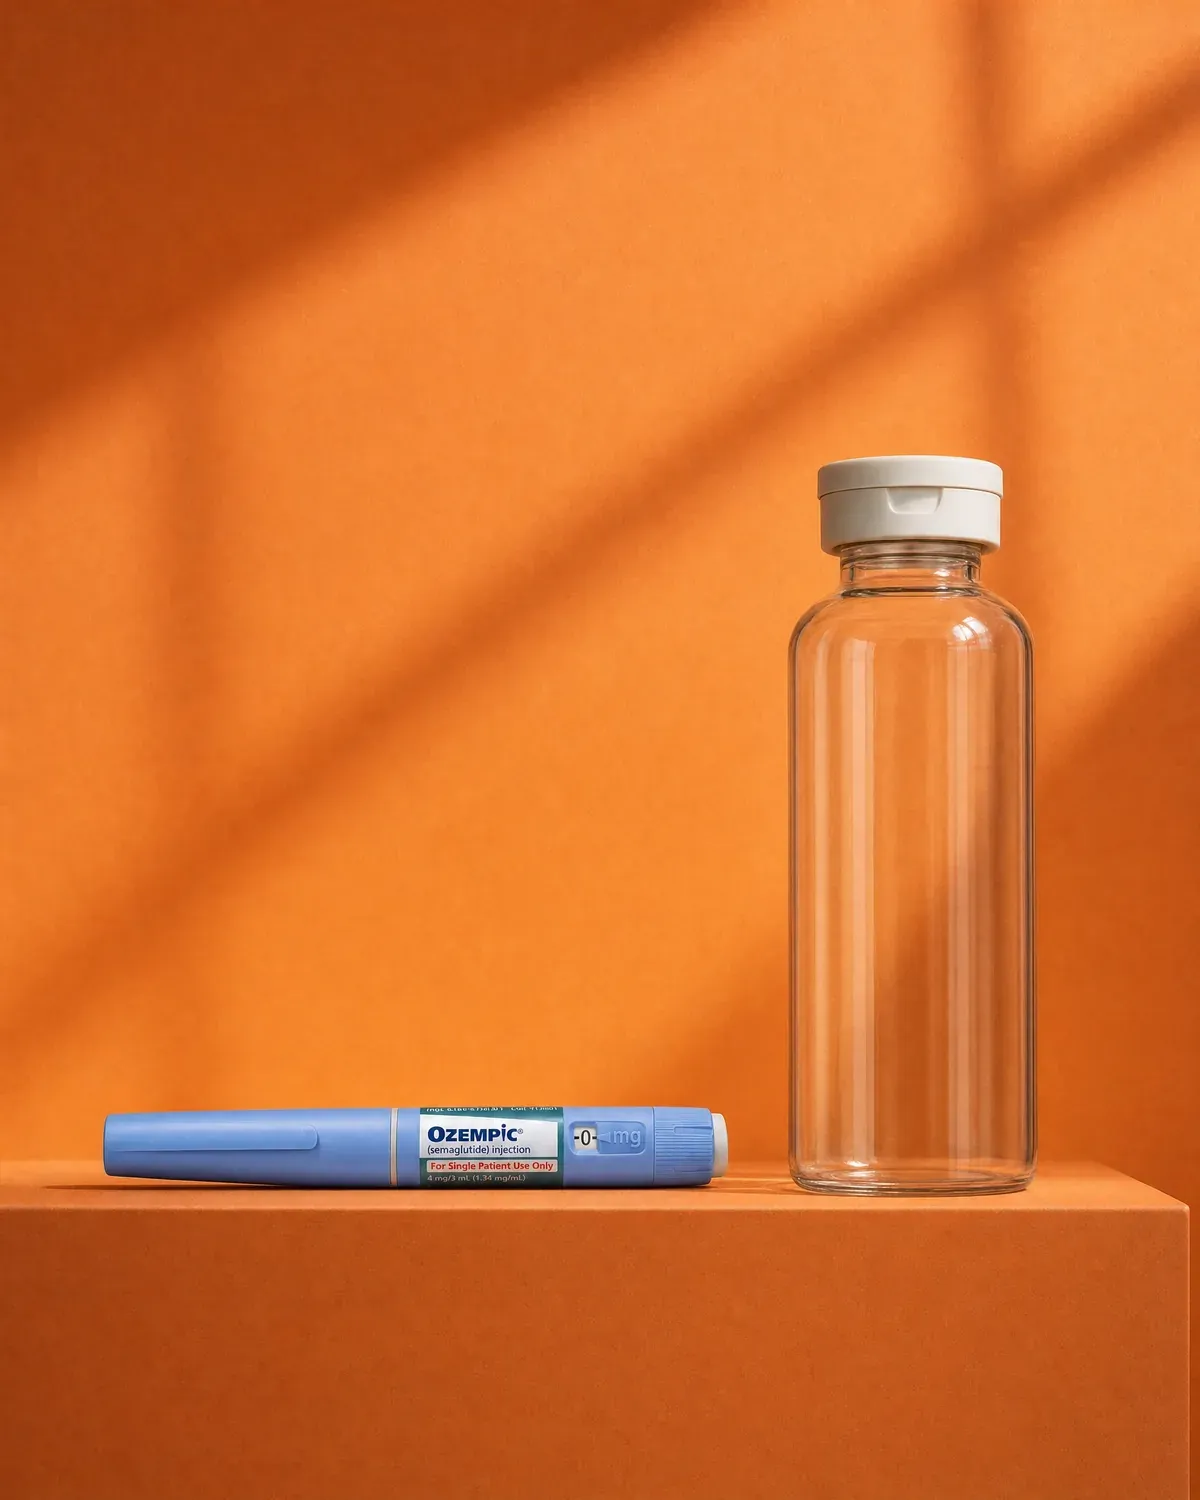
A plain, unbranded clinical-trial vial (retatrutide has no brand name) beside an Ozempic pen

Retatrutide climbs to sixth and passes Ozempic. It is still not approved by the FDA, but Lilly reported two more successful late-stage trials in July, and Reta's share of members rose 11% over the quarter while Ozempic's share of new members fell 7%. This trend is not unique to the MeAgain platform, as an early study of US health records (not yet peer reviewed) found its use growing about 80% a quarter, mostly outside of trials.

On the access side, Medicare's GLP-1 Bridge was the big story this quarter, letting eligible seniors get Wegovy, the Wegovy Pill, Foundayo and the Zepbound KwikPen for $50 a month. Seniors have been quick to sign up, with Lilly's CEO saying that about 700,000 had already started a GLP-1 through it (70% of them on a Lilly GLP-1). When we surveyed almost 20,000 MeAgain members in August, a significant number of older members reported recently getting approved for the Medicare Bridge Program at $50 a month. Foundayo, also covered by the Bridge, saw the fastest growth on the list, with its share of new MeAgain members up 44%. Lilly has also noted new Foundayo patients doubled from the second quarter, with about 40% of people starting a weight-loss pill now opting for Foundayo.

+44%rise in Foundayo's share of new MeAgain members in Q3 2026

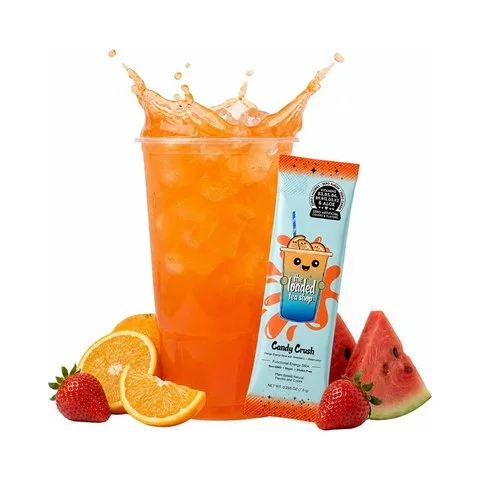
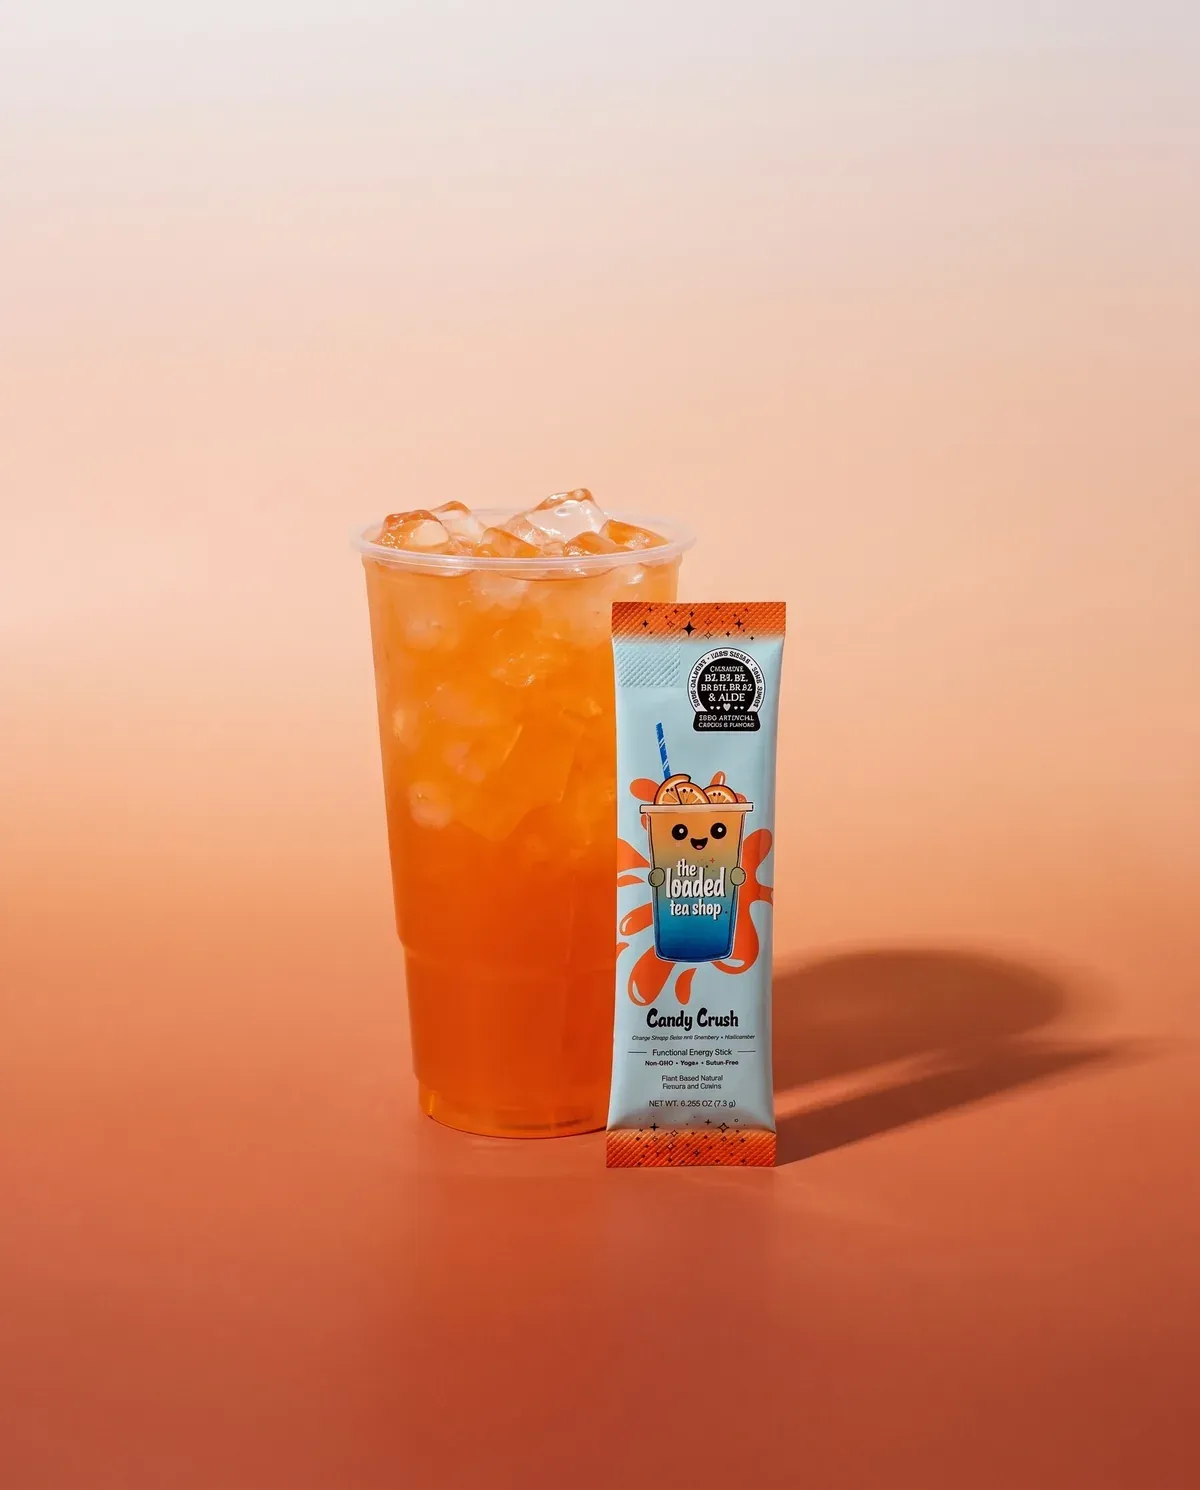
The Loaded Tea Shop Candy Crush energy stick and the drink made with it

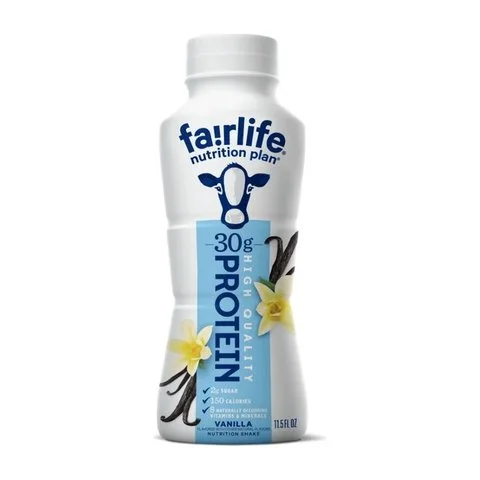
Fairlife's vanilla Nutrition Plan shake takes number one after Fairlife brought the fan favorite back to Costco, Sam's Club and BJ's on July 6th. It is comfortably the most consumed product on the list, and its return came alongside Fairlife's rise to the top of the brands list.

The Loaded Tea Shop's Candy Crush energy stick comes in second in its first full quarter of visibility on the MeAgain platform, and it is the most consumed energy drink or soda new to MeAgain this year. It picked up after the brand started marketing to women on GLP-1s in June. Getting enough water in can be challenging on a GLP-1, and a sugar-free stick that flavors water seems to be helping some. We surveyed more than 15,000 members in September on how they actually get their water in. Interestingly, well over 10% of the nearly 500 comments directly mentioned The Loaded Tea Shop as a core part of their daily routine for staying hydrated.

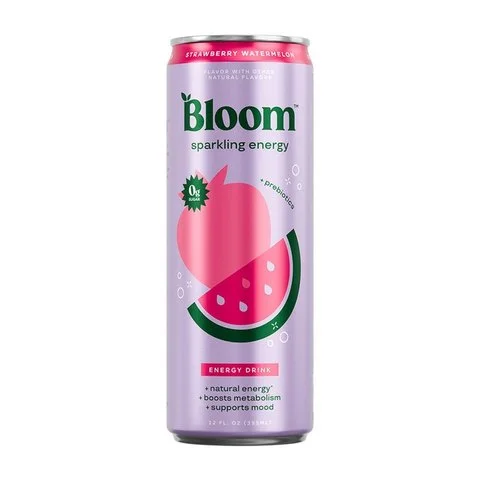
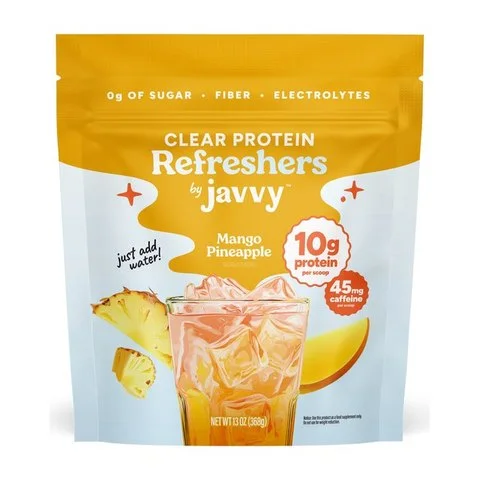
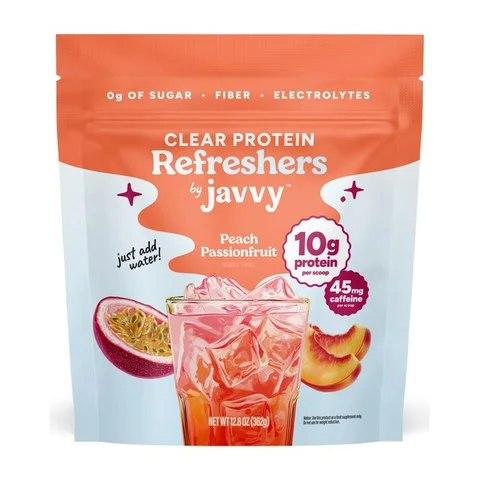
Bloom's Strawberry Watermelon sparkling energy drink is one of several fruit-flavored drinks that did well over the summer, coming in fifth after a new variety pack reached Costco in June. Consumption of Javvy's Mango Pineapple and Peach Passionfruit Clear Protein Refreshers, eighth and ninth, rose 389% and 351% as summer ads named both flavors.

+389%rise in consumption of Javvy's Mango Pineapple Clear Protein Refresher among MeAgain members in Q3 2026

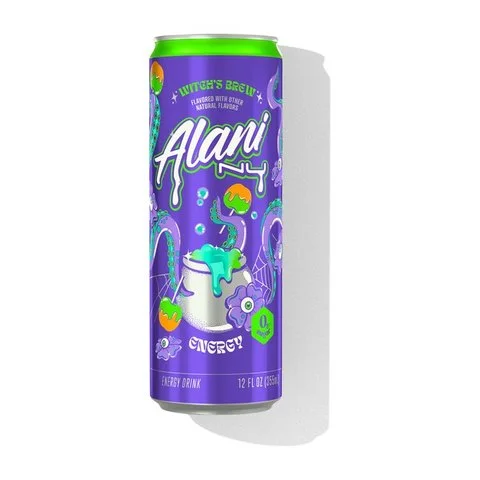
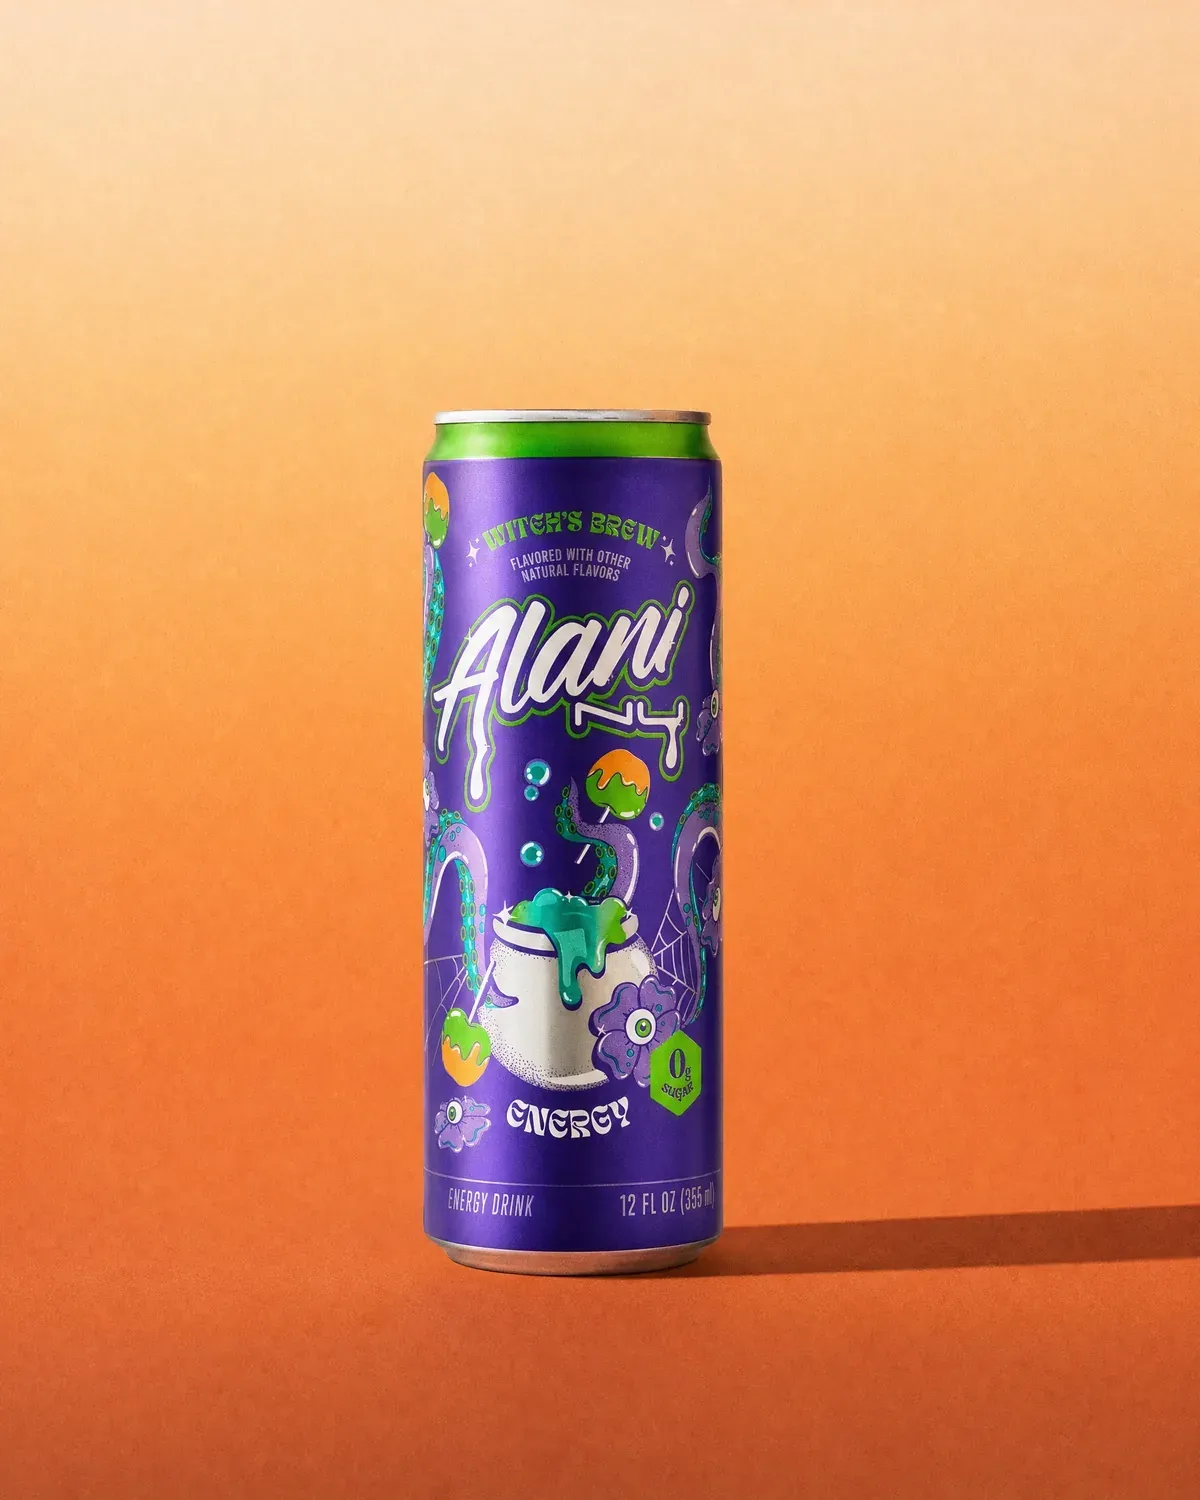
The Alani Nu Witch's Brew energy drink can

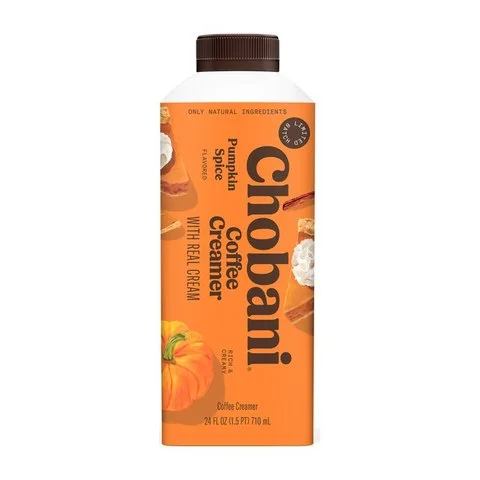
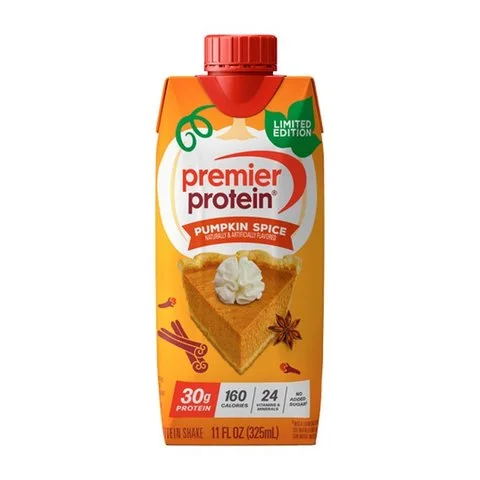
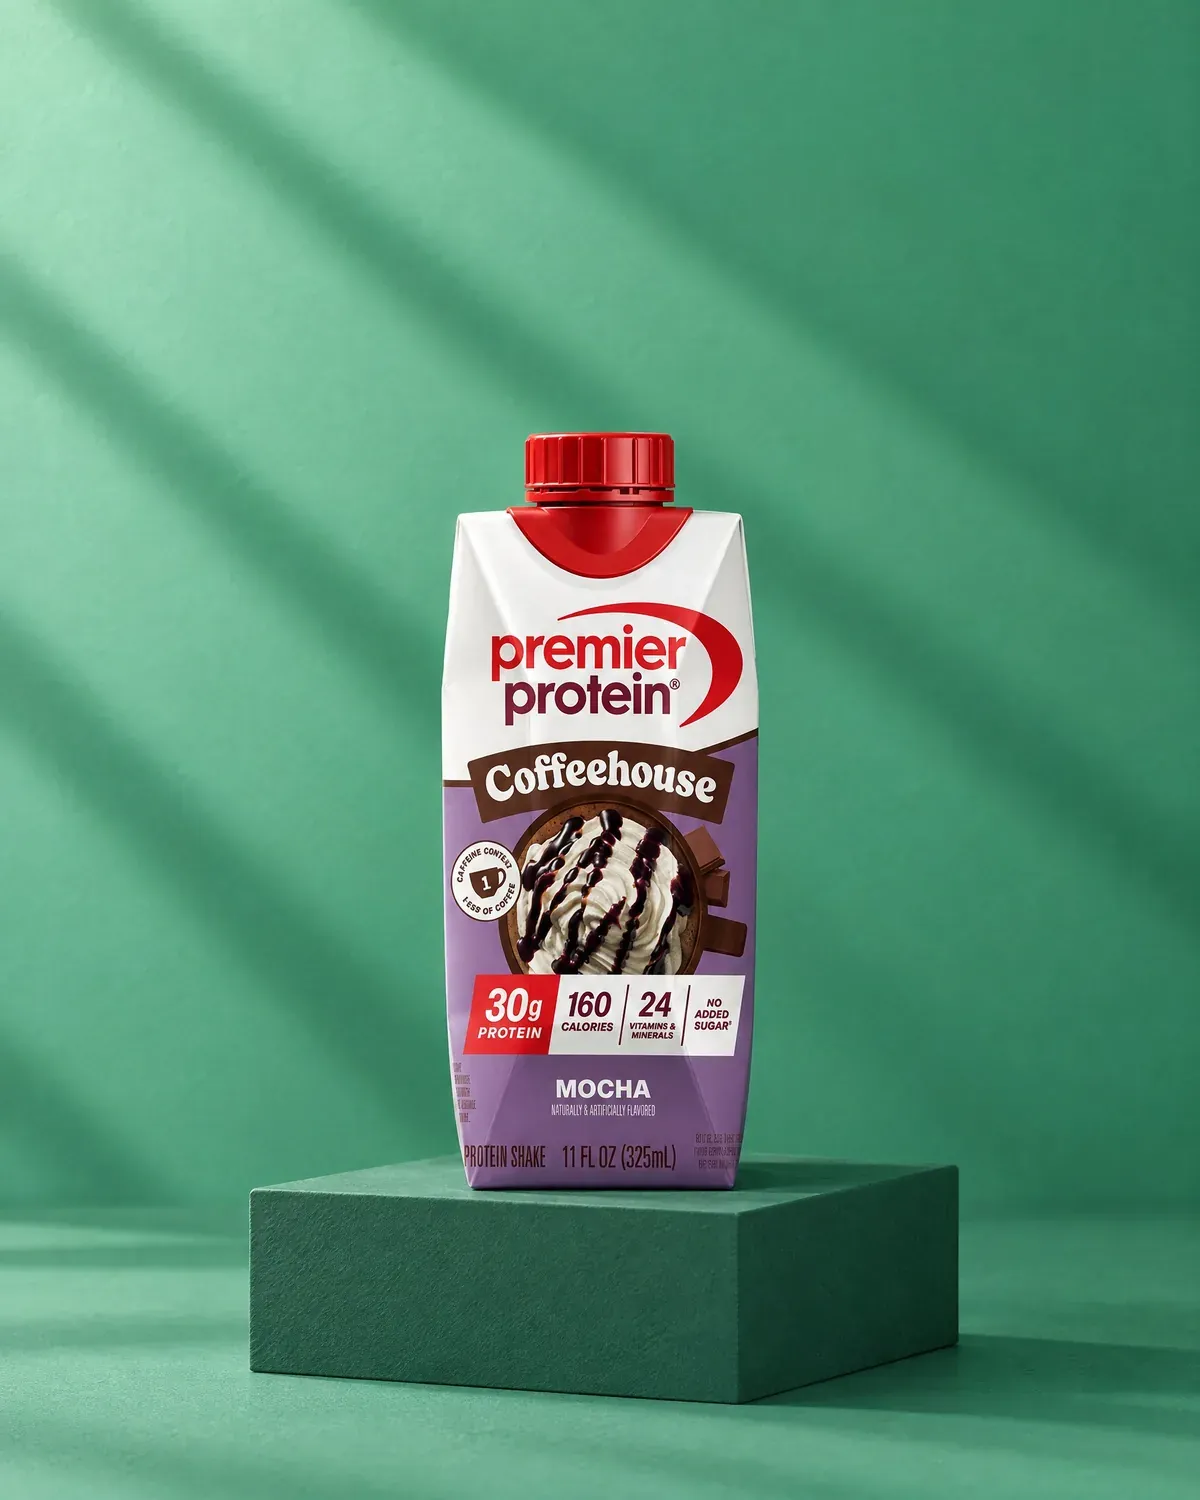
Fall flavors arrived early and took three places. Alani Nu's Witch's Brew is third after it returned on August 12th, and no energy drink was consumed by more MeAgain members this quarter. Chobani's pumpkin spice creamer, back on shelves by late July, lands in sixth place and was Food Network's top pumpkin spice pick of the season. Premier Protein's pumpkin spice shake, back in mid-August, is seventh and the most consumed pumpkin spice product on the MeAgain platform. With Fairlife's returning vanilla shake, four of the ten trending products were comebacks. These trends show that GLP-1 users, like other consumers, still seek variety and novel options to mix up their routines.

Babybel PRO, the brand's new protein and probiotic cheese, makes the list in fourth place in its first full quarter on the MeAgain platform. Launched at Target in March, it packs 5 grams of protein into a 50-calorie cheese and has been reaching more stores throughout the year.

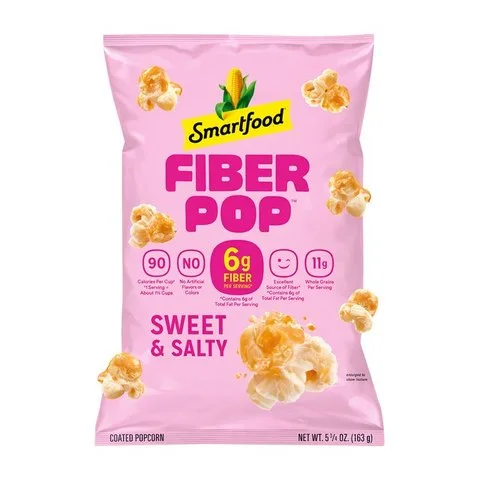
Fiber is back on the list. Smartfood Fiber Pop enters in tenth place as its consumption rose 487%. PepsiCo launched the popcorn early in the year with 6 grams of fiber a serving. PepsiCo's chief executive has said fiber will be the next protein.

Top GLP-1 Brands

Q3 2026

Top GLP-1 brands are ranked based on product diversity & availability, consumer adoption, GLP-1 needs alignment, product ratings & reviews, and online conversations.

  1. 01Fairlife1 place up
  2. 02Premier Protein1 place down
  3. 03ChobaniNo change
  4. 04OikosNo change
  5. 05QuestNo change
  6. 06Barebells3 places up
  7. 07MetamucilNew
  8. 08JavvyNew
  9. 09Vital Proteins2 places down
  10. 10DaisyNo change
  1. 11Great Value5 places up
  2. 12Mission6 places down
  3. 13Grüns5 places down
  4. 14Built3 places down
  5. 15Kodiak Cakes2 places down
  6. 16Kraft1 place down
  7. 17Trader Joe's2 places up
  8. 18Sargento1 place down
  9. 19Chomps5 places down
  10. 20Quaker2 places down

Dropped out

  • NurriLast quarter: 12
  • Nature ValleyLast quarter: 20
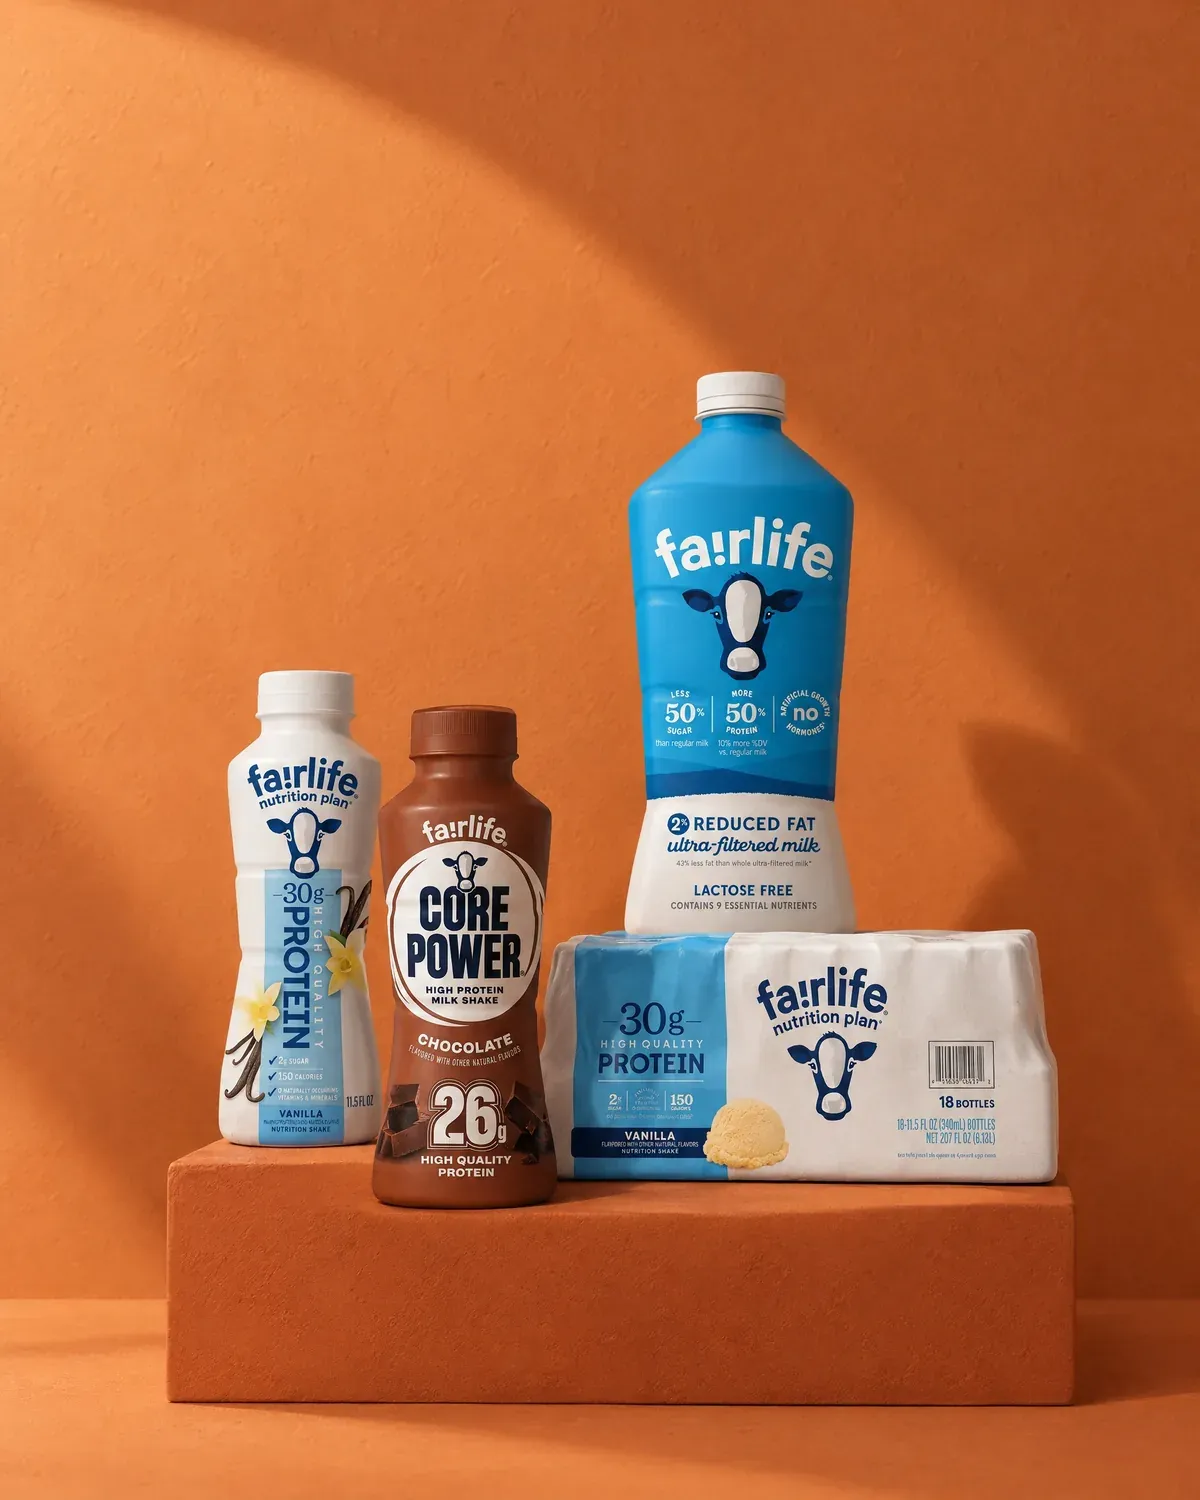
A range of Fairlife products: Nutrition Plan shakes, a Core Power shake and Fairlife ultra-filtered milk

Fairlife takes the top spot as the MeAgain Index adds members' ratings and reviews to the methodology this quarter. Fairlife averaged 4.84 out of 5, one of the highest ratings on the list and from far more ratings than the two brands rated higher. It is also the brand members mention most in conversations on the MeAgain platform. Notably, the return of its famous vanilla shake helped. Capacity is catching up with demand too. Its new plant in Webster, New York, began ramping up in August.

Premier Protein slips to second after two quarters at the top, as Fairlife earned a higher average rating in the newly released ratings and reviews on the MeAgain app. Despite falling to second, Premier Protein is pushing into new formats, with a 42-gram Ultimate shake in July and a sparkling protein soda in August, as protein soda moves into the mainstream.

When we surveyed more than 14,000 members in August, 45% still opted for a shake or protein coffee as their protein go-to, almost three times as often as chicken or meat. One of the reasons protein products are taking off is that people find it incredibly hard to hit their protein target. Out of the nearly 10,000 members we surveyed in July, 34% said that before starting a GLP-1 they had "no idea getting enough protein would be this hard," and that goes up to nearly 40% for members aged 60 and over, where getting enough protein is most critical.

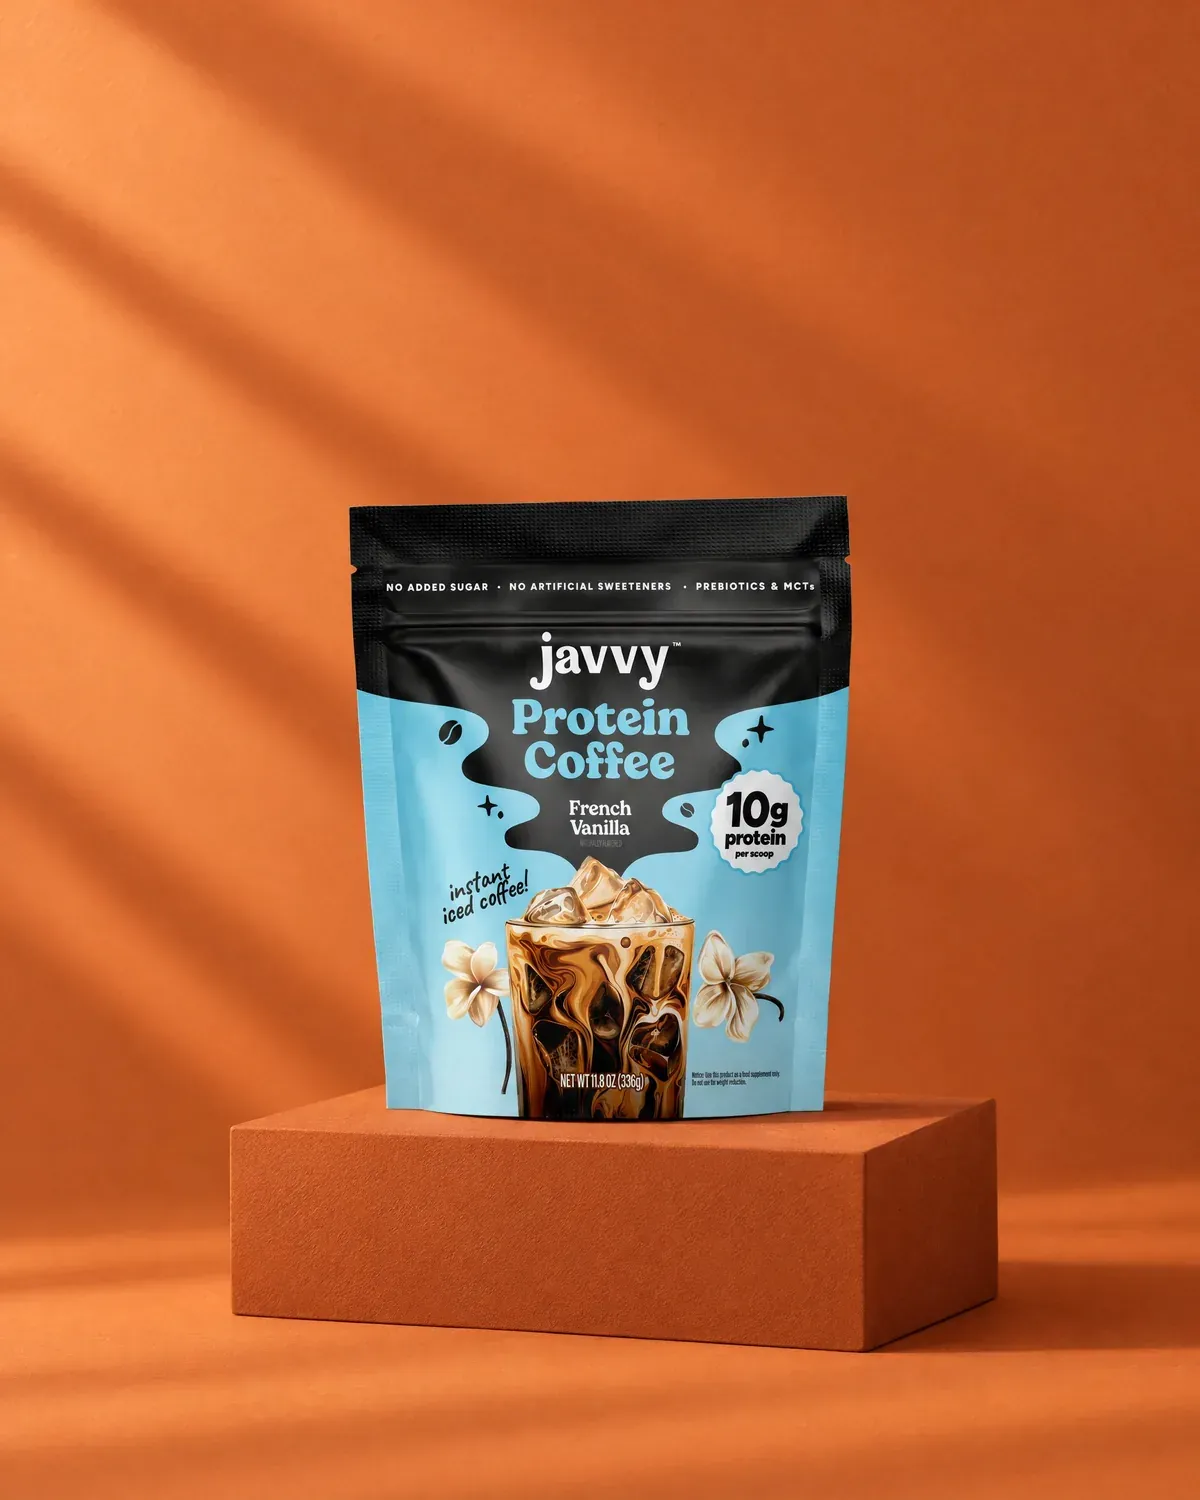
Metamucil fiber, a Javvy protein coffee and a Barebells bar together

Two new brands enter the top ten. Javvy, in eighth place, is the fastest-growing brand on the list. Its consumption rose 84% after its protein coffee reached more than 3,000 Walmarts in July. Members also explicitly mention having Javvy first thing in the morning in their survey responses, whether that is a protein refresher or a protein coffee. Metamucil, seventh, is one of the three brands members mention most in conversations on the platform, likely because it has been sold as "GLP-1 Friendly Fiber" since spring.

Great Value is the biggest climber, up five places to 11th, and is one of the most consumed brands on MeAgain. Mentions of it in GLP-1 social posts rose 51% after Walmart redesigned its packs to put protein on the front. The retailer is also more widely courting people on GLP-1s, with new support services for them in store and online. Barebells also climbs three places, to sixth, as its consumption rose 24% and its pumpkin spice bars returned for fall.

Three brands faced new rivals this quarter. Grüns falls five places to 13th after AG1, the biggest greens brand, launched its first greens gummies in August. Built slips three places to 14th as FitCrunch's marshmallow bar, a rival to Built Puff, reached Walmart in late July. Mission falls six places to 12th as store brands gained tortilla share. When a format takes off, competitors and store brands move in fast.

+84%rise in consumption of Javvy among MeAgain members in Q3 2026

Not every brand that moved up this quarter needed a new product, as Great Value and Metamucil showed that a familiar name with the right message can still win over people on GLP-1s.

Previous editionMeAgain IndexQ2 2026GLP-1 Pills Take Off, and Classic Meals Get Protein

The MeAgain Index

Press

index@meagain.com

How to cite

The MeAgain Index Q3 2026, MeAgain, meagain.com/index/q3-2026

All data aggregated and de-identified. Observational patterns from people who log in the MeAgain app, not causal claims. © Dots Future Technologies, Inc. 2026

About MeAgain: MeAgain is the largest neutral GLP-1 platform and has helped more than a million people start their GLP-1 journey. It uses its unique position in the market to give this independent, third-party view of the GLP-1 ecosystem. MeAgain is not affiliated with, sponsored by or endorsed by any brand, product or medicine named here. All brand names, product names and trademarks belong to their owners and are used only to identify them. Product images are illustrations.

Methodology

The MeAgain Index

Three GLP-1 lists, every quarter

  1. Top 10

    Leading GLP-1 Meds

    The leading GLP-1 meds are evaluated across pricing, insurance coverage, adoption, adherence, real-world weight loss outcomes, quality-of-life improvements, and new research.

  2. Top 10

    Trending GLP-1 Products

    The fastest-growing and most culturally relevant products for GLP-1 users in the quarter, based on new launches, real-world adoption, social media, AI search and other online conversations.

  3. Top 20

    Top GLP-1 Brands

    Top GLP-1 brands are ranked based on product diversity & availability, consumer adoption, GLP-1 needs alignment, product ratings & reviews, and online conversations.

How the MeAgain Index is calculated

The MeAgain Index methodology is built on three dimensions: Access, Use and Impact.

Access

01Is it easy to find?
Visibility in web search and AI assistants, sale through proper channels rather than the black market, and a wide range of GLP-1-friendly options.
02Is it easy to understand?
Clear labeling that shows it suits GLP-1 users, such as a high-protein claim. For medications, studies and other information published in terms the everyday consumer can understand and use for decision-making.
03Is it easy to buy?
Price, insurance coverage where it applies, how many pharmacies, stores and online shops sell it, and whether buying it needs a paid membership.

Use

01Do people consider using it?
Interest before people start, measured through social media conversation, AI search and general search volume.
02Do people start using it?
How many people bring a brand or product into their routine or start a medication, from real-world data on the MeAgain platform and third-party sources.
03Do people keep using it?
How many keep using or taking it, from repeat logging on the MeAgain platform and third-party data such as prescription refills.

Impact

01Does it improve health?
Health results such as weight loss among the people using it, alongside published third-party studies.
02Does it improve daily life?
Side effects, tone and sentiment from users on the MeAgain platform, case studies and third-party studies of wider effects, such as drinking less alcohol.
03Do people recommend it?
Posts and comments on Reddit, TikTok, Instagram and YouTube, plus ratings, reviews and polls on the MeAgain platform.

How to read the rankings

+3
Places up since last quarter
−2
Places down since last quarter
–
Same place as last quarter
New
New to the list this quarter
Dropped out
On last quarter's list, not on this one
Seasonal
A seasonal product

Unique combination of proprietary data and external sources

Depending on the signal, the MeAgain Index draws on proprietary data from hundreds of thousands of members on the MeAgain platform and tens of millions of data points. This is connected with external data sources and custom-built in-house tools that track the wider GLP-1 market, to give the most comprehensive view of GLP-1 use available. Figures from the MeAgain platform are adjusted for the growth of our member base.

How often the MeAgain Index is published

The MeAgain Index is published every quarter. Each dimension is scored and weighted using a proprietary model built by the MeAgain data team. The exact formula is not disclosed.

A living methodology

We expect the MeAgain Index to keep evolving as the MeAgain platform grows and GLP-1 treatment continues to change, and we will add new data sources once we are confident they are reliable enough to include. All figures are aggregated and anonymized, and we never show any individual's data.

For more information about the MeAgain Index please contact index@meagain.com