The MeAgain Index is a quarterly ranking of the leading GLP-1 meds, as well as top consumer brands and trending products serving GLP-1 users. Our proprietary methodology combines real-world behavioral data from hundreds of thousands of members on the MeAgain platform with signals from across the wider GLP-1 ecosystem, including clinical trial data, research publications, product launches, third-party reported data, social media trends and emerging AI discovery channels.

Period
Jan 1 – Mar 31, 2026
Published
October 2026
Based on
Hundreds of thousands of MeAgain members
Methodology

Lilly Leads Meds, and Protein Leads Everything Else

Eli Lilly's medicines take the top two spots on the first MeAgain Index, and protein is the central theme on the food lists. Trending products are dominated by protein shakes, bars and yogurts, and the top four brands are all built on high-protein dairy.

Leading GLP-1 Meds

Q1 2026

The leading GLP-1 meds are evaluated across pricing, insurance coverage, adoption, adherence, real-world weight loss outcomes, quality-of-life improvements, and new research.

  1. 01ZepboundNo change
  2. 02MounjaroNo change
  3. 03Compounded tirzepatide†No change
  4. 04WegovyNo change
  5. 05OzempicNo change
  1. 06Compounded semaglutide†No change
  2. 07Retatrutide*No change
  3. 08Wegovy PillNo change
  4. 09VictozaNo change
  5. 10TrulicityNo change

†Compounded versions are prepared by pharmacies and are not FDA-approved.

*Retatrutide is an investigational medicine that is not FDA-approved. Lilly plans to file for approval in early 2027; it has no brand name yet. Its place on the list is not a recommendation.

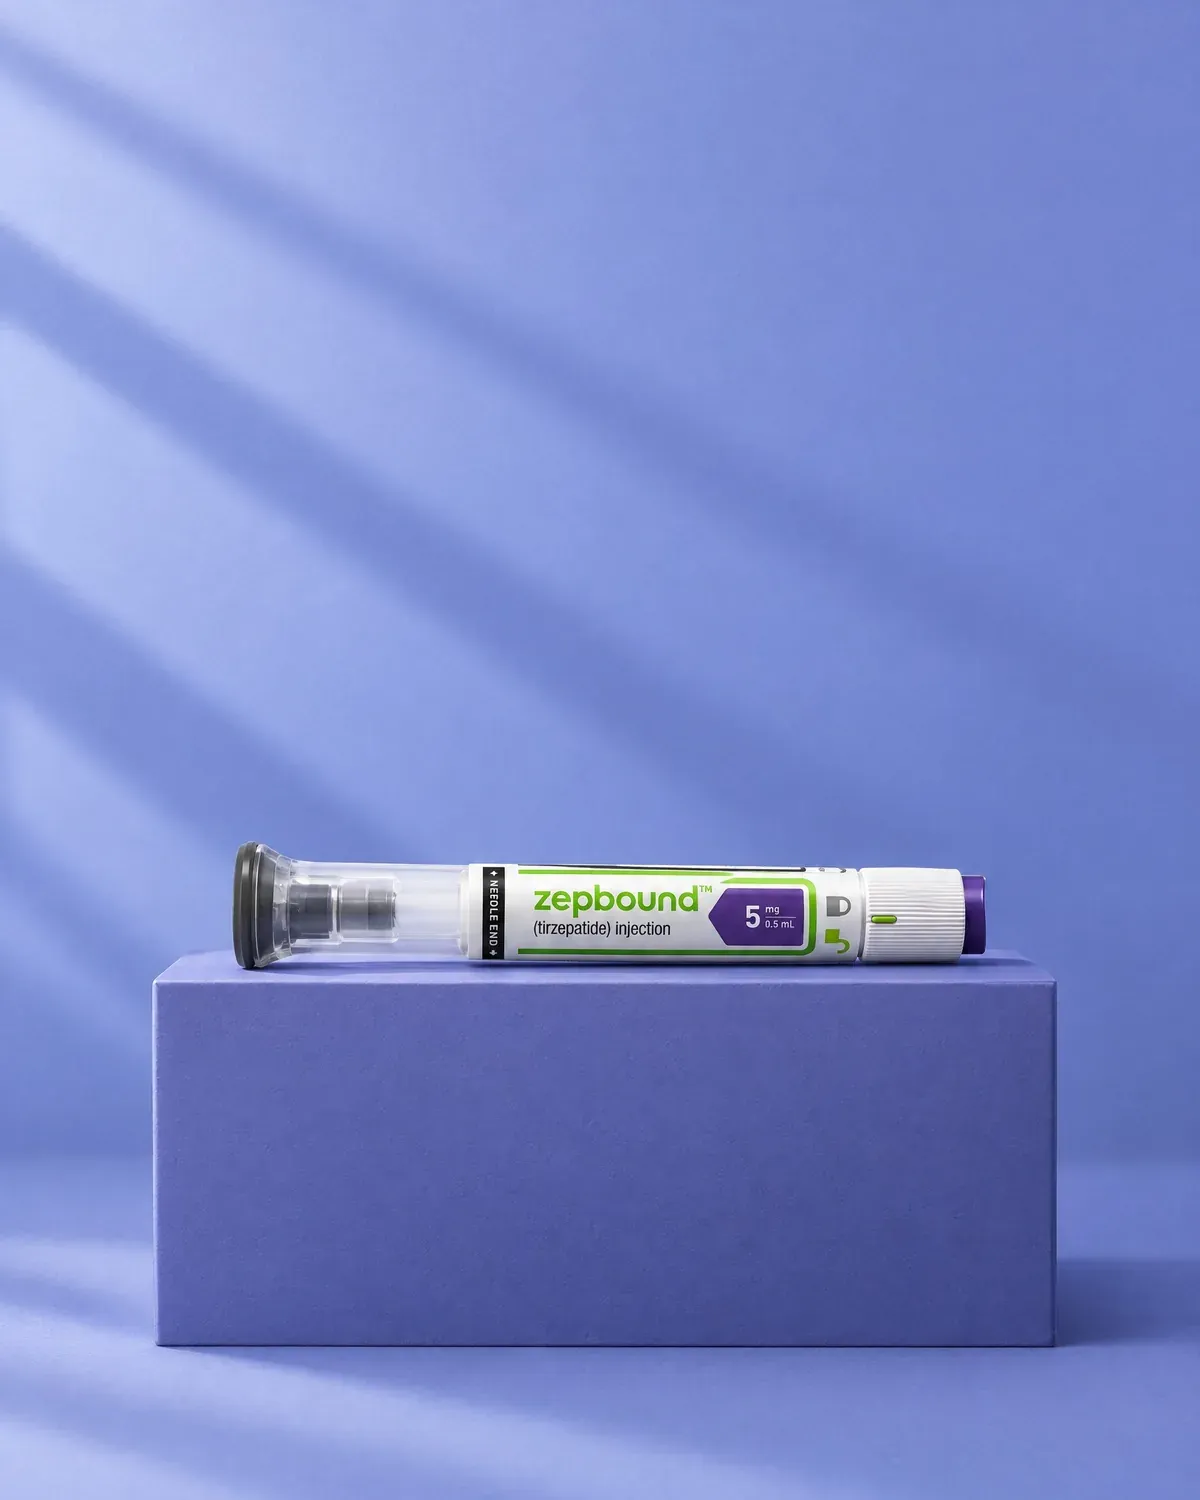
Different tirzepatide injectables: a Zepbound pen, a Mounjaro pen and a plain compounding-pharmacy vial

Zepbound and Mounjaro, both from Lilly, take first and second place on the first Leading GLP-1 Meds list. Not only are they among the most used GLP-1s on the MeAgain platform, but members on Zepbound also recorded one of the highest median weight losses for the quarter in our real-world dataset. The continued demand for Lilly medicines came as Lilly lowered out-of-pocket costs, cutting Zepbound vial prices in December, launching the KwikPen at the same price in Q1 and listing Zepbound on TrumpRx from $299. Direct-to-consumer GLP-1s have continued to go mainstream. One in three new patients starting a branded weight-loss drug in 2025 began on Zepbound self-pay vials.

Compounded tirzepatide completes the top three. Its share of new members rose 20% from the end of 2025, making it the most common GLP-1 of choice for new members this quarter. The rise came as four state Medicaid programs stopped covering GLP-1s for weight loss in January, and it is not just Medicaid that is pulling back. The share of large employers covering the drugs for weight loss has fallen from 72% in 2025 to 60% this year.

+20%rise in compounded tirzepatide's share of new MeAgain members in Q1 2026
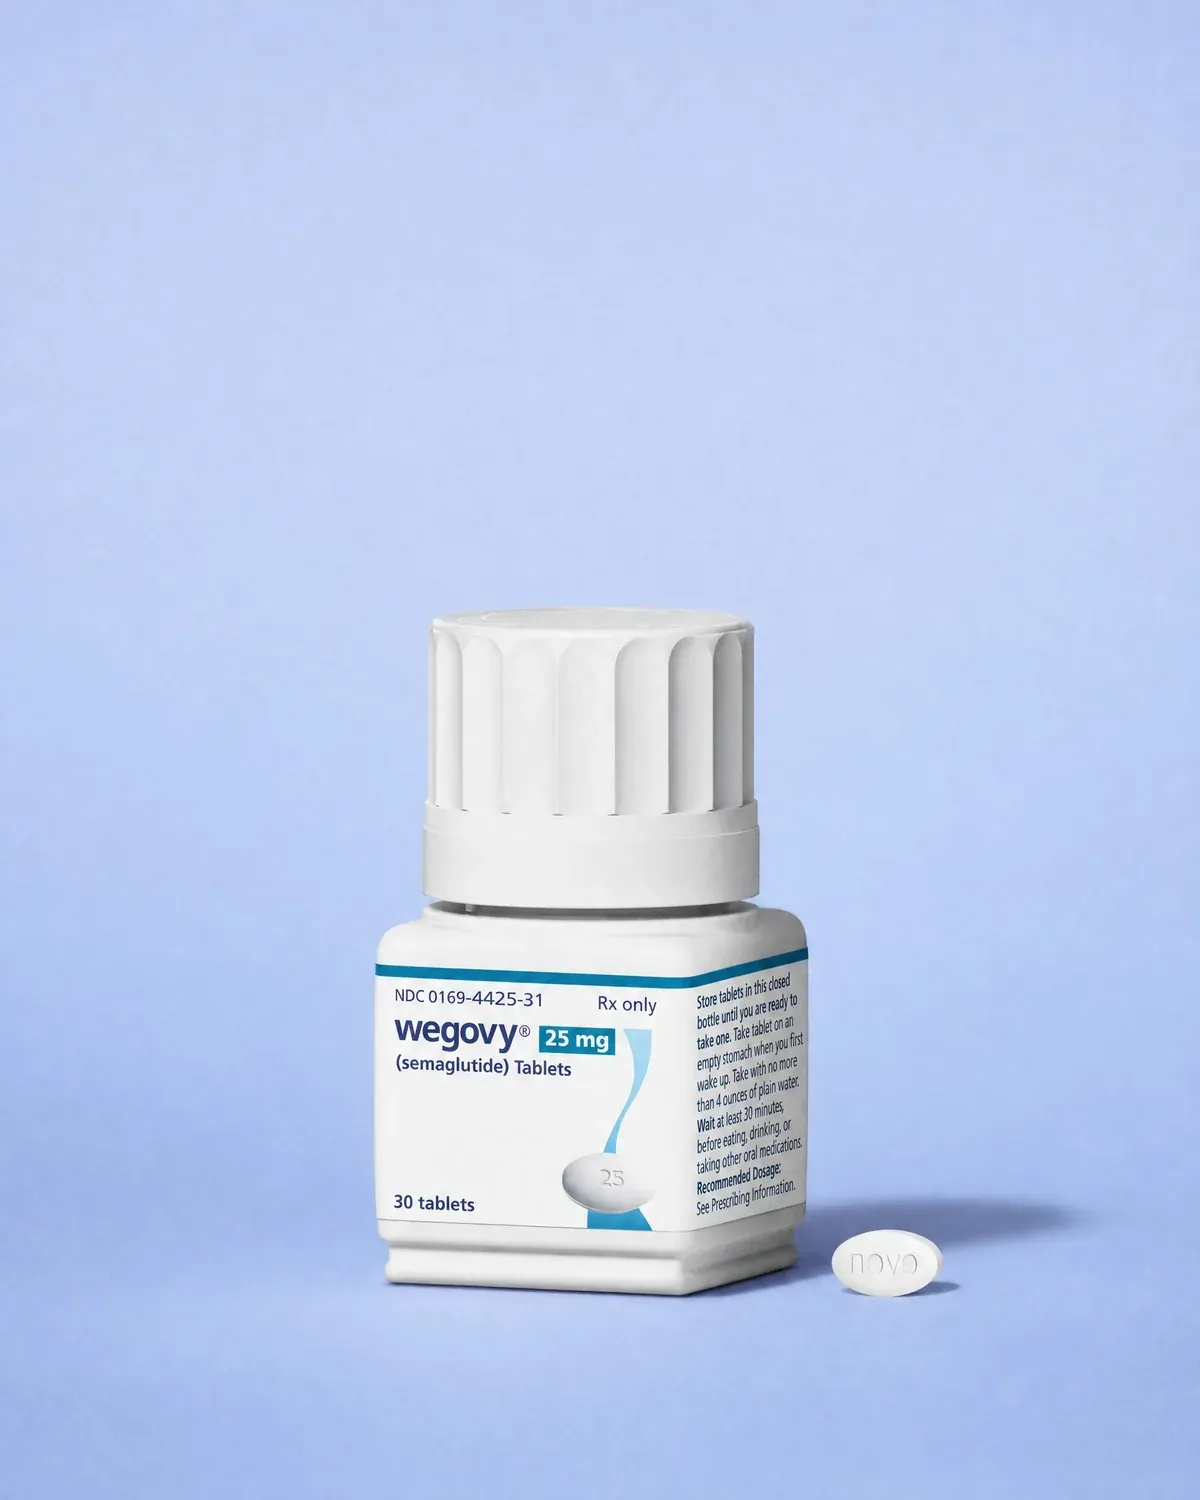
A Wegovy pill mockup: the Wegovy pill pack with a single tablet beside it

The Wegovy Pill enters the list in eighth place. Novo launched it nationwide on January 5th, a long-awaited addition to the GLP-1 market, letting people wary of injections start a GLP-1 for the first time. A Super Bowl ad in February gave it a further boost as Novo looked to capitalize on an early-mover advantage. The launch was a success with fast early uptake. First-quarter sales came in at almost double what analysts expected, and 3.5% of new MeAgain members in the quarter selected the Wegovy Pill.

Across the list, the first-quarter theme was about access to branded GLP-1s. Novo cut Wegovy's cash price from $499 to $349 a month late last year, and TrumpRx listed Wegovy and Ozempic from $199 when it opened in February. Telehealth companies also moved toward branded medicines in the quarter. Hims & Hers started offering branded Wegovy again in March after the FDA said in February it would act against mass-marketed compounded GLP-1s.

As insurers continue to pull back, GLP-1s for weight loss may become a cash-only market, where branded and compounded medicines compete on price.

3.5%of new MeAgain members chose the Wegovy Pill in Q1 2026, its first quarter on sale

Trending GLP-1 Products

Q1 2026

The fastest-growing and most culturally relevant products for GLP-1 users in the quarter, based on new launches, real-world adoption, social media, AI search and other online conversations.

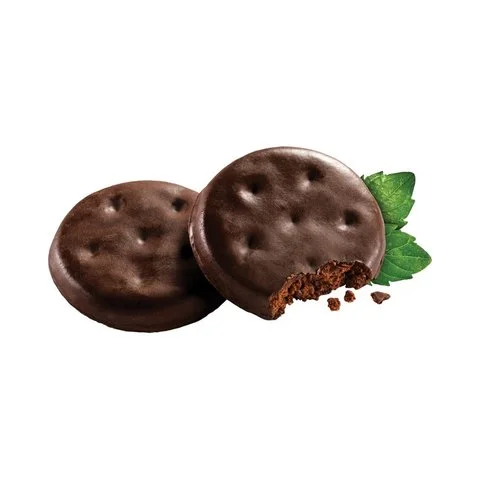
  1. 01SeasonalGirl ScoutsThin Mints Cookies
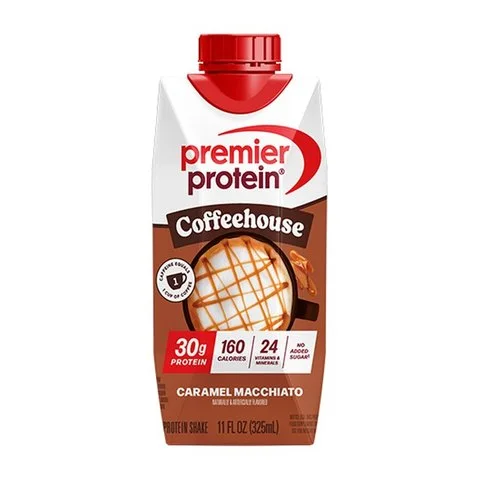
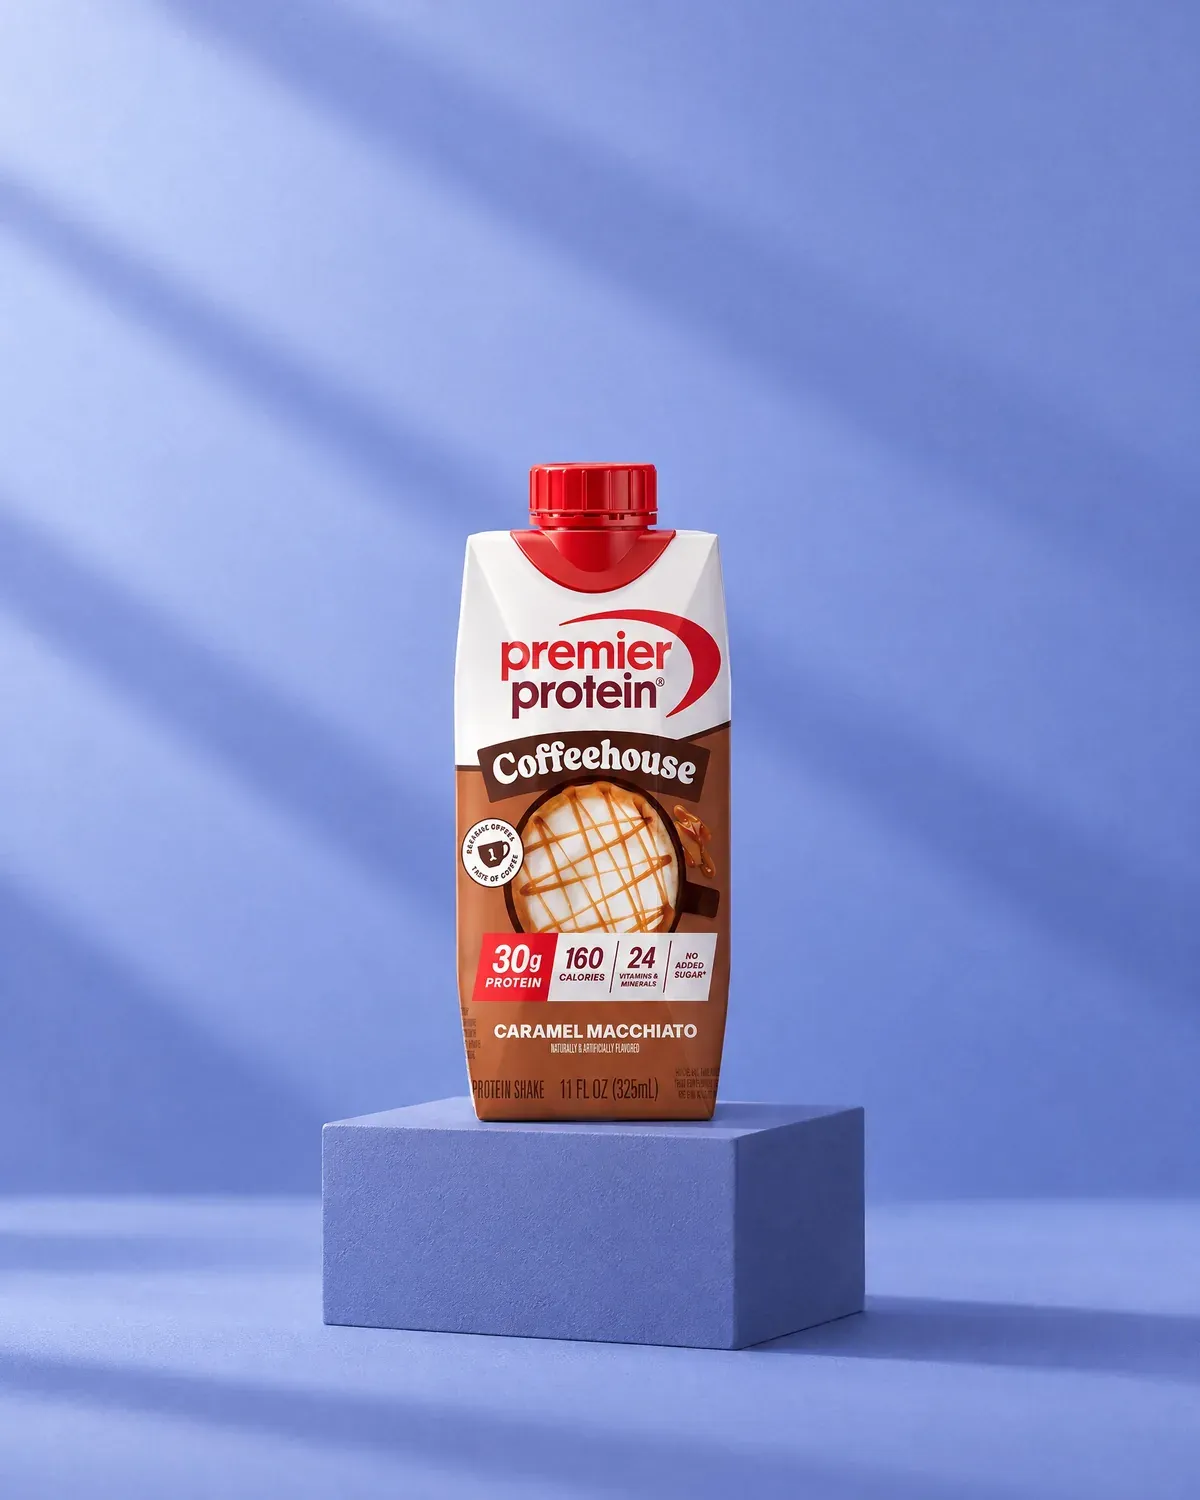
  2. 02Premier ProteinCaramel Macchiato Protein Shake
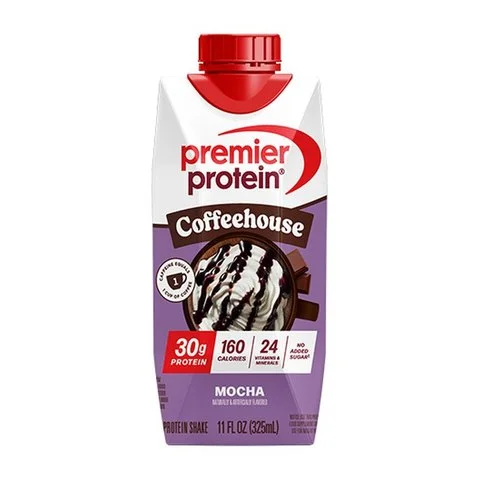
  3. 03Premier ProteinMocha Protein Shake
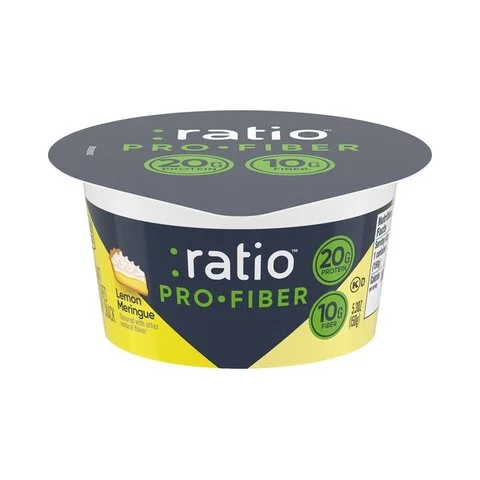
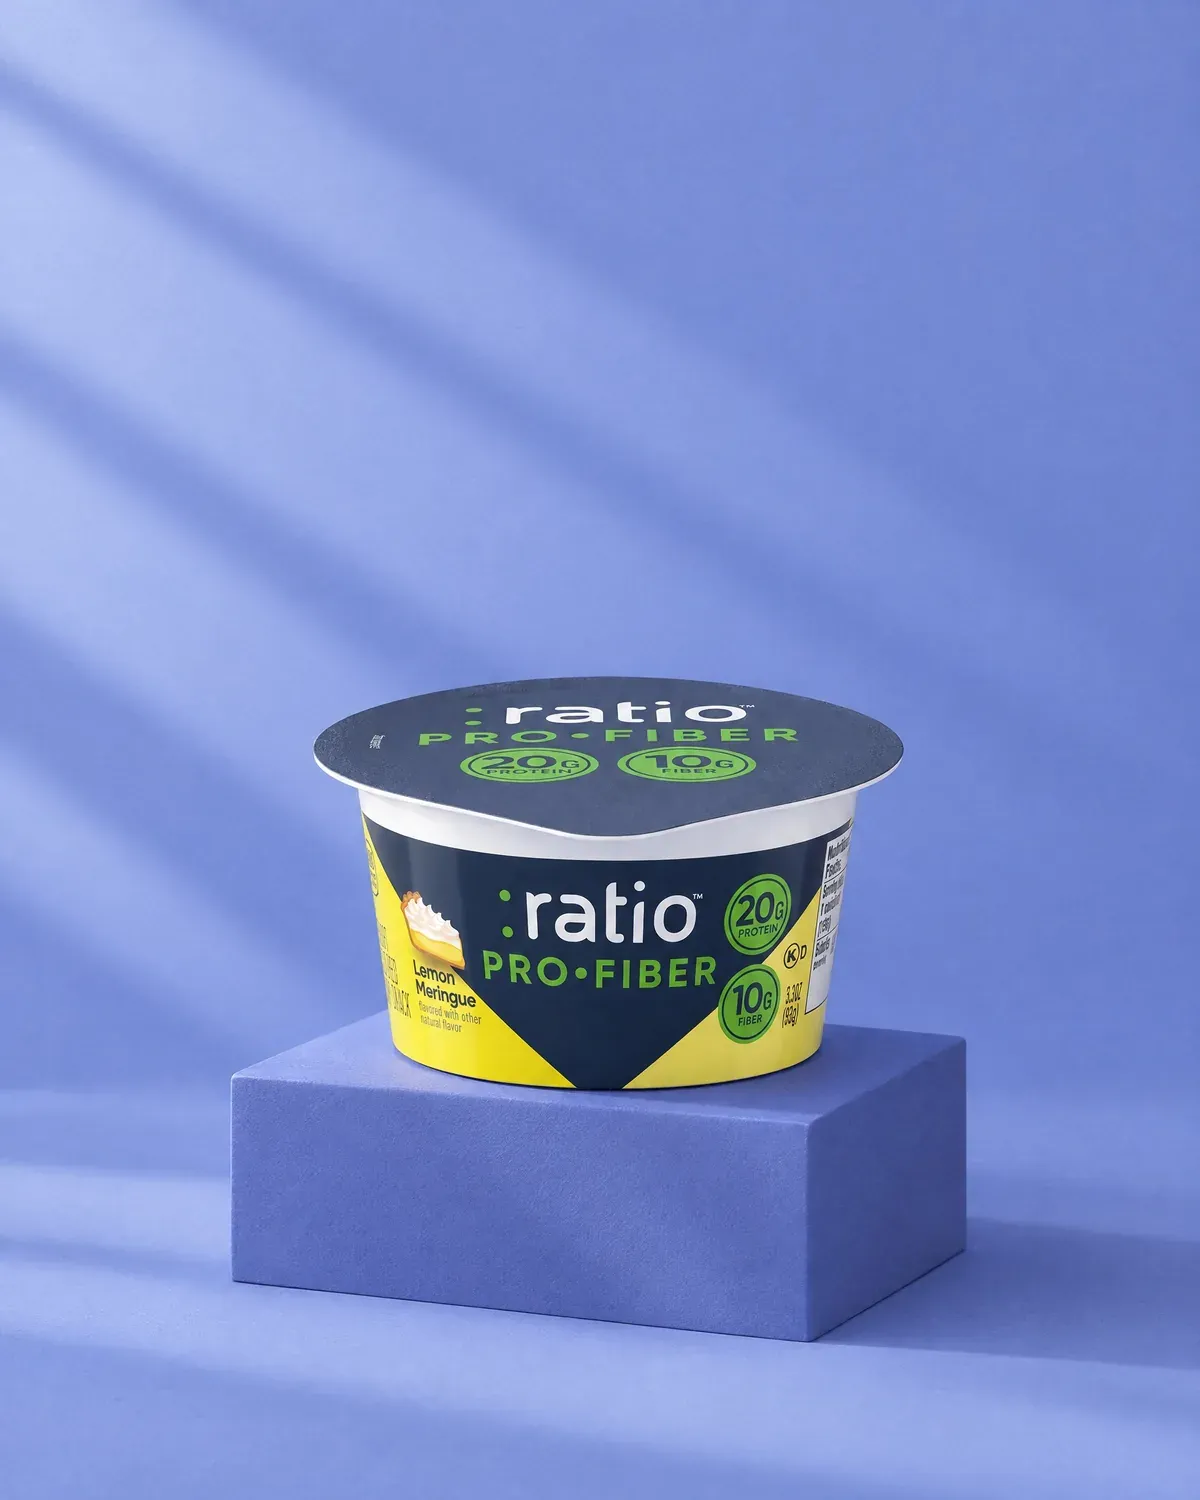
  4. 04RatioPro Fiber Yogurt Lemon Meringue
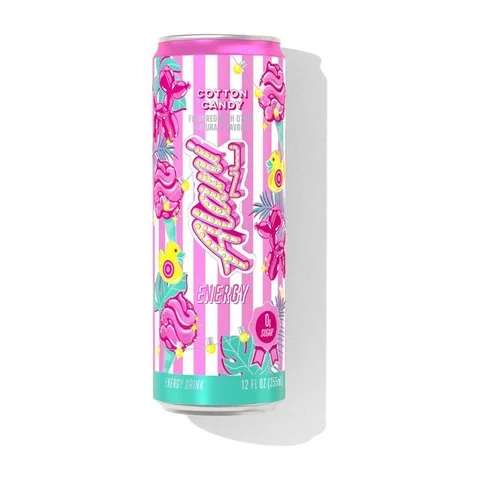
  5. 05Alani NuCotton Candy Energy Drink
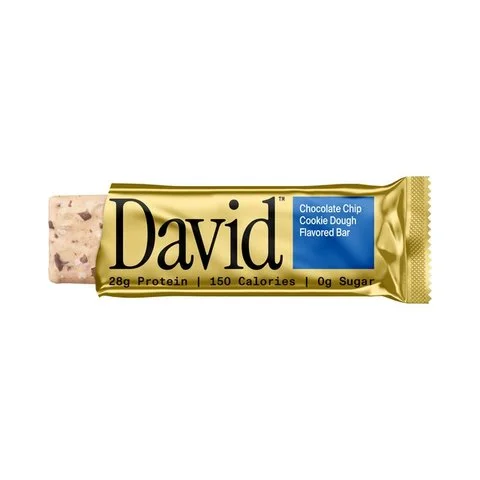
  6. 06DavidProtein Bar Chocolate Chip Cookie Dough
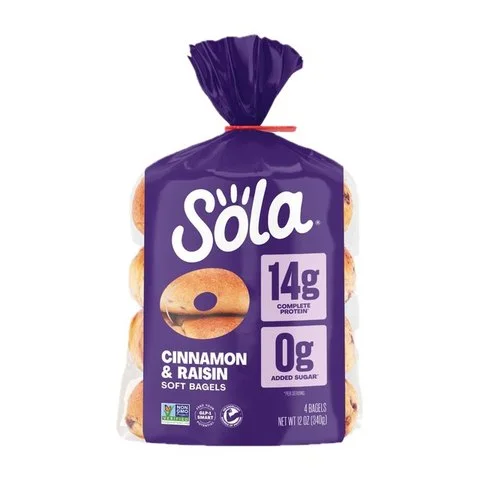
  7. 07SolaCinnamon & Raisin Bagels
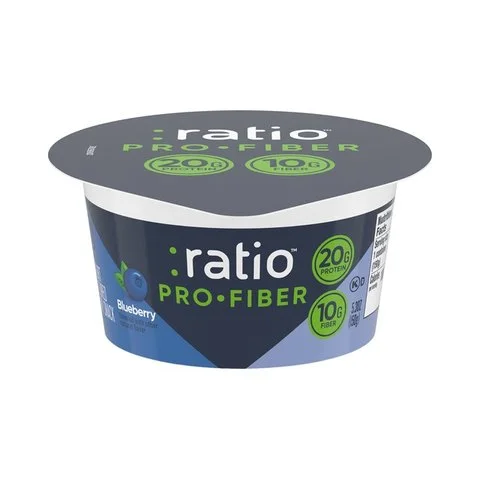
  8. 08RatioPro Fiber Yogurt Blueberry
  9. 09Simply FuelChocolate Coconut Peanut Butter Protein Balls
  10. 10DavidProtein Bar Peanut Butter Chocolate Chunk
Girl Scouts Thin Mints cookies

Girl Scouts' Thin Mints top the first Trending GLP-1 Products list as cookie season opened nationwide on January 6th. More MeAgain members consumed them than any other product on the list, and Girl Scouts list Thin Mints first among their best-selling cookies. The presence of Girl Scout Cookies at the top of the list suggests GLP-1 users are seeking to find balance by making room for a treat they can only buy once a year.

Premier Protein's two new caffeinated coffee shakes follow, with Caramel Macchiato in second place and Mocha in third. They were two of the most consumed new protein shakes on the MeAgain platform, helped by widespread distribution on shelves (physical and online) nationwide. Walmart and Amazon both carried them by late February.

Alani Nu's Cotton Candy energy drink makes the list in fifth place. Its consumption rose 338% after the brand made the sold-out summer flavor a year-round one in December. It rode a wider surge for the brand. Alani Nu's US retail sales rose 77% in the last three months of 2025, according to its owner Celsius.

Both Ratio Pro Fiber yogurt cups, Lemon Meringue and Blueberry

Fiber joins protein on the list. Consumption of :ratio's Lemon Meringue Pro-Fiber yogurt rose 316%, and its Blueberry flavor rose 153%, in their first full quarter on sale. Lactalis (parent company of :ratio) launched the snack nationwide in November and sold it as GLP-1 friendly. The timing was right. In January, CNN called fiber the next big thing after protein.

Protein snacks reached more shoppers. David went nationwide at Target and Walmart in the first quarter. Consumption of its Chocolate Chip Cookie Dough bar rose 232%, landing it in sixth place, while its Peanut Butter Chocolate Chunk bar, tenth, rose 164%. Simply Fuel's protein balls, ninth, rose 148%.

Eight of the ten trending products this quarter are built around protein or fiber, from coffee shakes and bars to snack balls, yogurt and a high-fiber bagel from Sola in seventh place. Big food makers are chasing the same shift. PepsiCo, Coca-Cola and Nestlé are all adding high-fiber products. People on a GLP-1 eat less, so they look for more protein and fiber in every portion.

+316%rise in consumption of :ratio Pro-Fiber Lemon Meringue among MeAgain members in Q1 2026
Top GLP-1 Brands

Q1 2026

Top GLP-1 brands are ranked based on product diversity & availability, consumer adoption, GLP-1 needs alignment, product ratings & reviews, and online conversations.

  1. 01Premier ProteinNo change
  2. 02FairlifeNo change
  3. 03OikosNo change
  4. 04ChobaniNo change
  5. 05QuestNo change
  6. 06BuiltNo change
  7. 07MissionNo change
  8. 08NurriNo change
  9. 09BarebellsNo change
  10. 10Vital ProteinsNo change
  1. 11GrünsNo change
  2. 12Great ValueNo change
  3. 13DaisyNo change
  4. 14Kodiak CakesNo change
  5. 15ChompsNo change
  6. 16QuakerNo change
  7. 17Trader Joe'sNo change
  8. 18KraftNo change
  9. 19SargentoNo change
  10. 20Jimmy DeanNo change
The leading brands together: a Premier Protein shake, a Fairlife Nutrition Plan shake, an Oikos Pro drink and a Chobani Greek yogurt

Premier Protein leads the first Top GLP-1 Brands list, with MeAgain members consuming more Premier Protein than any other brand. The company also continues to add new products consistently, such as its new caffeinated Coffeehouse shakes. The timing suited a protein-first moment. The new US Dietary Guidelines, published in January, push Americans to prioritize protein at every meal. Premier Protein's owner calls it the leading ready-to-drink protein shake in the US, with 22% of the category.

Fairlife takes second place. It is also the second most consumed brand by MeAgain members despite significant supply-side constraints of late. Coca-Cola kept Fairlife on allocation to stores while it waited for new capacity. This may only be temporary as Coca-Cola committed $650 million to expanding Fairlife's Michigan plant, on top of a new plant in New York.

Greek yogurt takes the next two places, with Oikos third and Chobani fourth, by far the most popular yogurt brands among MeAgain members in the quarter. Oikos ran a Super Bowl ad starring Kathryn Hahn and Derrick Henry on February 8th. Beyond being strong established brands among GLP-1 users, they are also growing fast. Chobani's 2025 sales rose 29% to $3.8 billion, and Oikos passed €1 billion in US sales, with its owner Danone saying that demand for protein keeps on rising, especially among people on GLP-1s.

A range of protein bars: a Quest bar, a Built Puff and a Barebells bar

Grüns, in 11th place, had the biggest rise in consumption of any brand on the list, up 10% for the quarter, and it was a big quarter for the brand on the retail side too, with its greens gummies landing at H-E-B, Hy-Vee and Wegmans in January and February, then at Costco nationwide in March. Nurri comes in eighth and is getting a lot more attention, with mentions of it in GLP-1 social posts up 57% after its first ad campaign in January and a move into Target in March.

A few of the names on the list have been around for decades. Great Value, Walmart's own label, comes in 12th and is one of the most consumed brands on the MeAgain platform, which shows our members are not only buying specialty brands. Mission takes seventh and draws the most positive GLP-1 social posts of any brand on the list after it pitched its tortillas for simple meals for people on GLP-1s in January. Daisy is 13th, and its cottage cheese has been selling well of late, with sales up 25% in the year ending in February, while in January the brand also ran new ads calling it a protein-packed essential.

We are also seeing the brands that started out with protein bars branch out into new formats. Quest, in fifth place, launched new Crispy Protein Chips at Walmart on March 2nd. Barebells, ninth, put its milk drink into about 2,000 Walmarts in January. Protein is moving beyond the bar, so bar brands now compete with chip and drink makers too.

+57%rise in mentions of Nurri in GLP-1 social posts in Q1 2026

Not only do the big protein names lead the first list, but newer brands like Grüns and Nurri are already finding room next to them, which suggests there is still plenty of space for brands built with GLP-1 users in mind.

The MeAgain Index

Press

index@meagain.com

How to cite

The MeAgain Index Q1 2026, MeAgain, meagain.com/index/q1-2026

All data aggregated and de-identified. Observational patterns from people who log in the MeAgain app, not causal claims. © Dots Future Technologies, Inc. 2026

About MeAgain: MeAgain is the largest neutral GLP-1 platform and has helped more than a million people start their GLP-1 journey. It uses its unique position in the market to give this independent, third-party view of the GLP-1 ecosystem. MeAgain is not affiliated with, sponsored by or endorsed by any brand, product or medicine named here. All brand names, product names and trademarks belong to their owners and are used only to identify them. Product images are illustrations.

Methodology

The MeAgain Index

Three GLP-1 lists, every quarter

  1. Top 10

    Leading GLP-1 Meds

    The leading GLP-1 meds are evaluated across pricing, insurance coverage, adoption, adherence, real-world weight loss outcomes, quality-of-life improvements, and new research.

  2. Top 10

    Trending GLP-1 Products

    The fastest-growing and most culturally relevant products for GLP-1 users in the quarter, based on new launches, real-world adoption, social media, AI search and other online conversations.

  3. Top 20

    Top GLP-1 Brands

    Top GLP-1 brands are ranked based on product diversity & availability, consumer adoption, GLP-1 needs alignment, product ratings & reviews, and online conversations.

How the MeAgain Index is calculated

The MeAgain Index methodology is built on three dimensions: Access, Use and Impact.

Access

01Is it easy to find?
Visibility in web search and AI assistants, sale through proper channels rather than the black market, and a wide range of GLP-1-friendly options.
02Is it easy to understand?
Clear labeling that shows it suits GLP-1 users, such as a high-protein claim. For medications, studies and other information published in terms the everyday consumer can understand and use for decision-making.
03Is it easy to buy?
Price, insurance coverage where it applies, how many pharmacies, stores and online shops sell it, and whether buying it needs a paid membership.

Use

01Do people consider using it?
Interest before people start, measured through social media conversation, AI search and general search volume.
02Do people start using it?
How many people bring a brand or product into their routine or start a medication, from real-world data on the MeAgain platform and third-party sources.
03Do people keep using it?
How many keep using or taking it, from repeat logging on the MeAgain platform and third-party data such as prescription refills.

Impact

01Does it improve health?
Health results such as weight loss among the people using it, alongside published third-party studies.
02Does it improve daily life?
Side effects, tone and sentiment from users on the MeAgain platform, case studies and third-party studies of wider effects, such as drinking less alcohol.
03Do people recommend it?
Posts and comments on Reddit, TikTok, Instagram and YouTube, plus ratings, reviews and polls on the MeAgain platform.

How to read the rankings

+3
Places up since last quarter
−2
Places down since last quarter
–
Same place as last quarter
New
New to the list this quarter
Dropped out
On last quarter's list, not on this one
Seasonal
A seasonal product

Unique combination of proprietary data and external sources

Depending on the signal, the MeAgain Index draws on proprietary data from hundreds of thousands of members on the MeAgain platform and tens of millions of data points. This is connected with external data sources and custom-built in-house tools that track the wider GLP-1 market, to give the most comprehensive view of GLP-1 use available. Figures from the MeAgain platform are adjusted for the growth of our member base.

How often the MeAgain Index is published

The MeAgain Index is published every quarter. Each dimension is scored and weighted using a proprietary model built by the MeAgain data team. The exact formula is not disclosed.

A living methodology

We expect the MeAgain Index to keep evolving as the MeAgain platform grows and GLP-1 treatment continues to change, and we will add new data sources once we are confident they are reliable enough to include. All figures are aggregated and anonymized, and we never show any individual's data.

For more information about the MeAgain Index please contact index@meagain.com