The MeAgain Index is a quarterly ranking of the leading GLP-1 meds, as well as top consumer brands and trending products serving GLP-1 users. Our proprietary methodology combines real-world behavioral data from hundreds of thousands of members on the MeAgain platform with signals from across the wider GLP-1 ecosystem, including clinical trial data, research publications, product launches, third-party reported data, social media trends and emerging AI discovery channels.

Period
Apr 1 – Jun 30, 2026
Published
October 2026
Based on
Hundreds of thousands of MeAgain members
Methodology

GLP-1 Pills Take Off, and Classic Meals Get Protein

GLP-1 pills took off with three making the list for Q2. Then, some of the best-known names in food added protein to their classics this quarter, with Kraft's mac and cheese, Starbucks' bottled coffee and Doritos all making the lists. By June, MeAgain members were consuming protein versions of 37 everyday foods, about a third more than at the end of 2025.

Leading GLP-1 Meds

Q2 2026

The leading GLP-1 meds are evaluated across pricing, insurance coverage, adoption, adherence, real-world weight loss outcomes, quality-of-life improvements, and new research.

  1. 01ZepboundNo change
  2. 02MounjaroNo change
  3. 03Compounded tirzepatide†No change
  4. 04WegovyNo change
  5. 05Wegovy Pill3 places up
  1. 06Ozempic1 place down
  2. 07Retatrutide*No change
  3. 08Compounded semaglutide†2 places down
  4. 09FoundayoNew
  5. 10Ozempic pillNew

Dropped out

  • VictozaLast quarter: 09
  • TrulicityLast quarter: 10

†Compounded versions are prepared by pharmacies and are not FDA-approved.

*Retatrutide is an investigational medicine that is not FDA-approved. Lilly plans to file for approval in early 2027; it has no brand name yet. Its place on the list is not a recommendation.

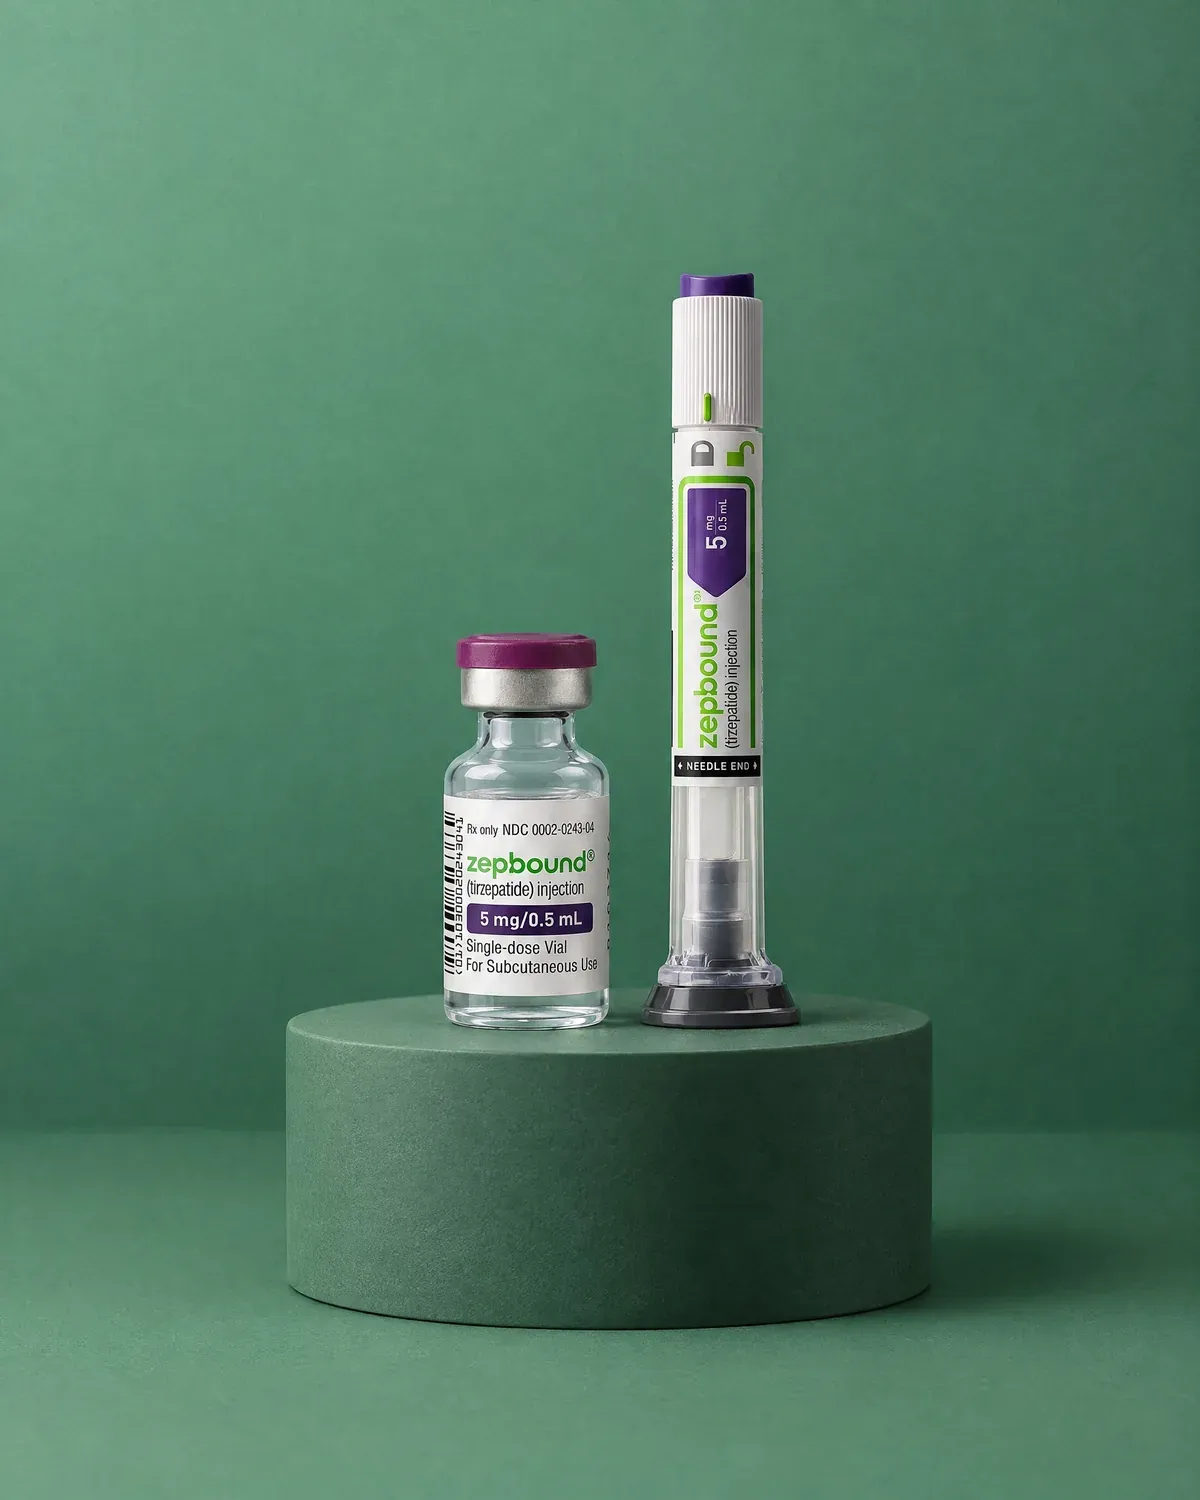
Tirzepatide injectables: Zepbound vials and a Zepbound pen

Zepbound holds the top spot as its share of new MeAgain members rose 8% in the quarter. The rise came as Hims & Hers began sending Zepbound prescriptions to Lilly's online pharmacy, LillyDirect, in April, and Lilly also noted US sales of Zepbound rose 44% in the second quarter.

Compounded GLP-1s lost ground. Compounded semaglutide drops two places to eighth, as its share of new members fell 36%, the biggest fall on the list. Compounded tirzepatide holds third, though its share of new members fell 15%. Both declines came amid closer scrutiny of companies selling compounded GLP-1s. In March, the FDA sent warning letters to 30 telehealth firms over how they marketed compounded GLP-1s.
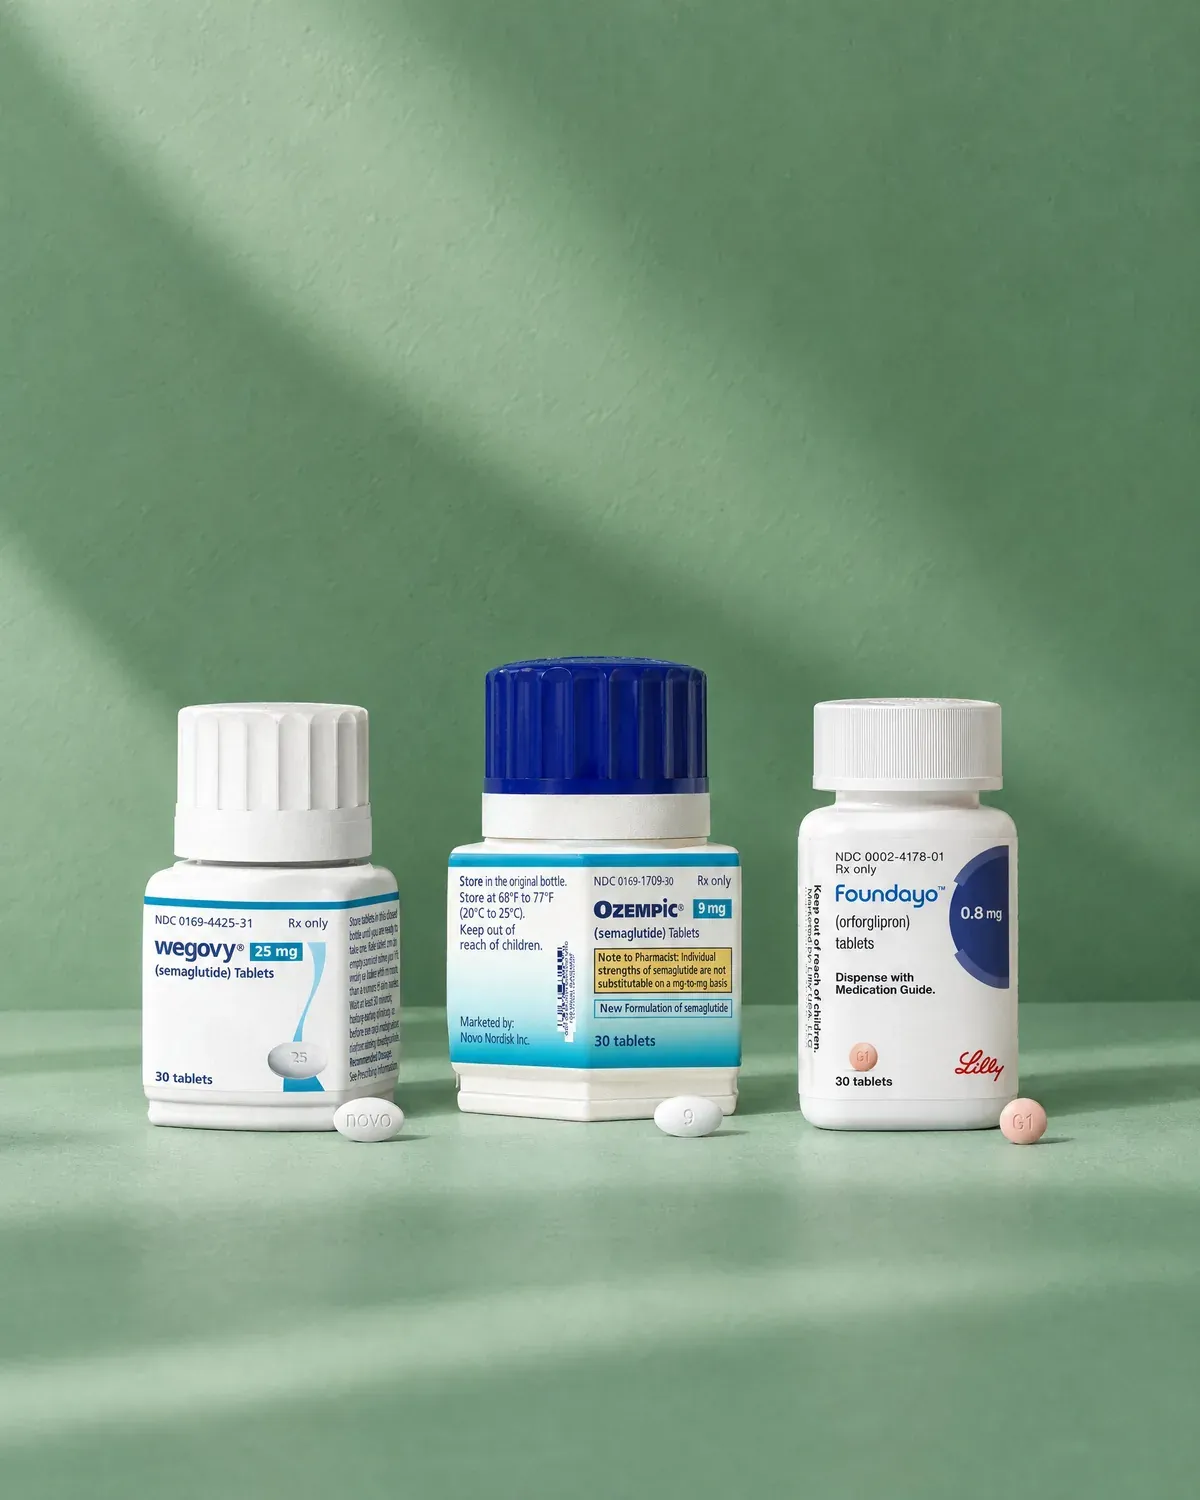
The three GLP-1 pills on the list: the Wegovy pill, Foundayo and the Ozempic pill, each pack with a tablet

The Wegovy Pill is the quarter's biggest climber, up three places to fifth, as its share of new members rose 146%. By early June, the pill had passed 3 million US prescriptions in just over five months on sale. This growth comes after Novo made several strategic moves on the marketing side, including launching subscriptions that bring its higher doses down to $249 a month. Beyond bringing down prices, the multi-month subscriptions aim to improve long-term adherence, which remains one of the biggest challenges in the GLP-1 ecosystem.

Three GLP-1 pills are now on the list at once. Lilly's Foundayo makes its debut in ninth place after it went on sale on April 9th from $149 a month. In its launch quarter, 0.7% of new members are on Foundayo, a good start, but not as strong as the Wegovy Pill's 3.5% in its first quarter. The Ozempic pill also enters, in tenth place, after Novo relaunched its Rybelsus diabetes pill under the Ozempic name on May 4th.

Pills are bringing new people to GLP-1s. The makers say more than 80% of new Wegovy Pill prescriptions and 80% of Foundayo's go to people new to the drugs. They are mostly growing the market, not taking patients from injections.

+146%rise in the Wegovy Pill's share of new MeAgain members in Q2 2026

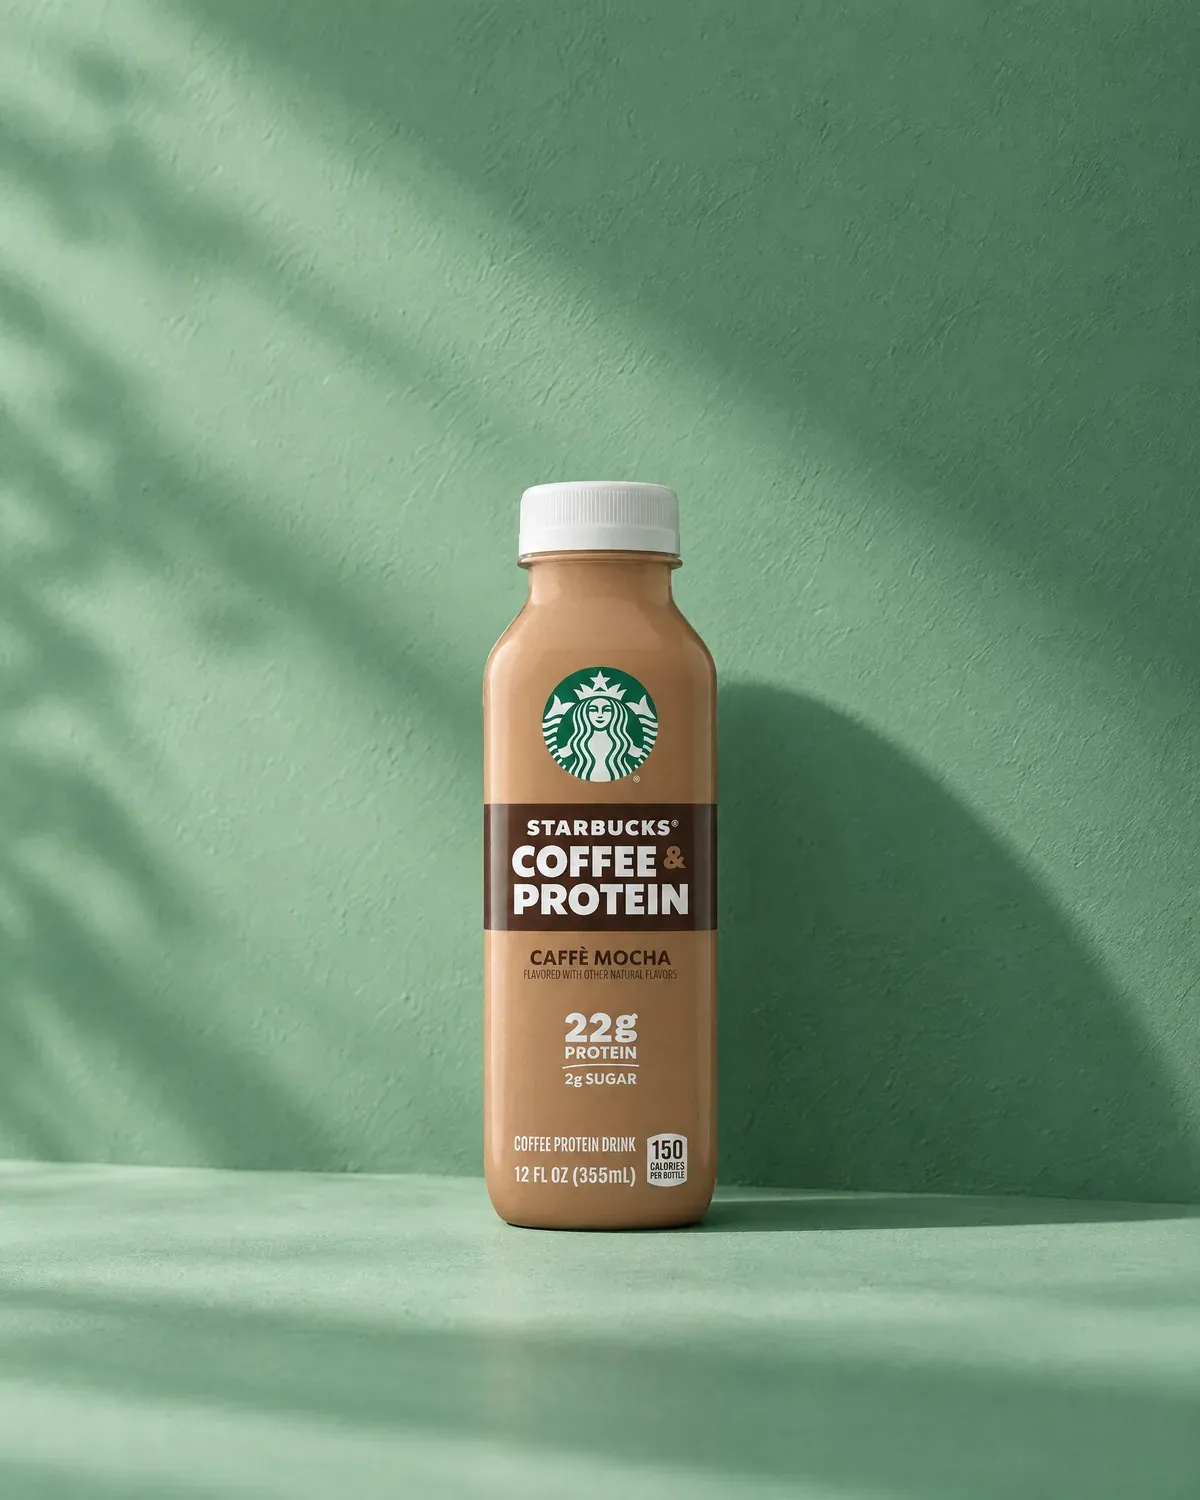
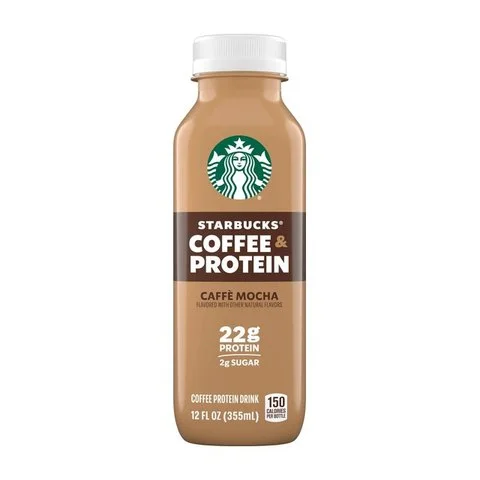
The bottled Starbucks Caffe Mocha coffee protein drink

Starbucks' bottled Caffè Mocha Coffee Protein Drink takes the top spot in its first full quarter on sale, after reaching stores nationwide on March 23rd. More MeAgain members consumed it than any other product new to the MeAgain platform this year. Starbucks has been open about who this is for, with its CEO tying the company's protein launches to the rise of GLP-1s. It tops a list where six of the ten trending products are drinkable protein, showing the importance of protein density for GLP-1 users.

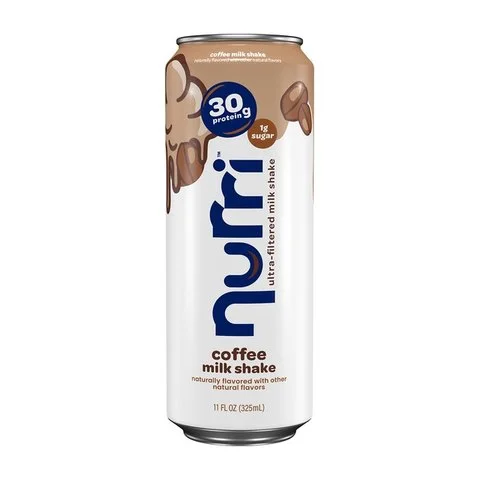
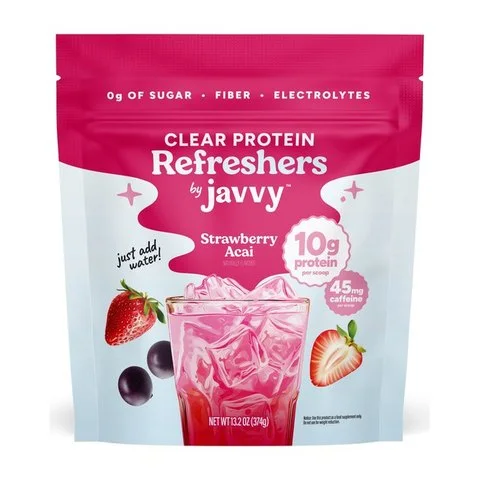
Other new protein drinks climbed fast too, with Nurri's Coffee shake, another coffee and protein duo, coming in fourth as its consumption rose 399%. Javvy's Strawberry Acai Clear Protein Refresher enters in sixth place in its first full quarter, after launching in March on Amazon and at Target.

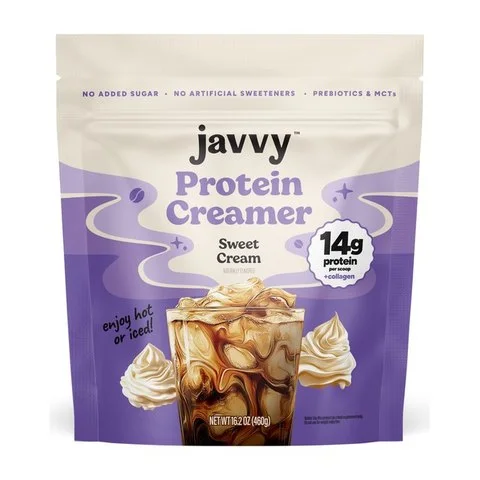
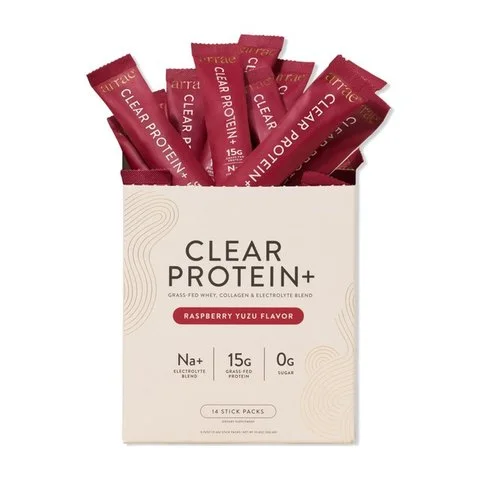
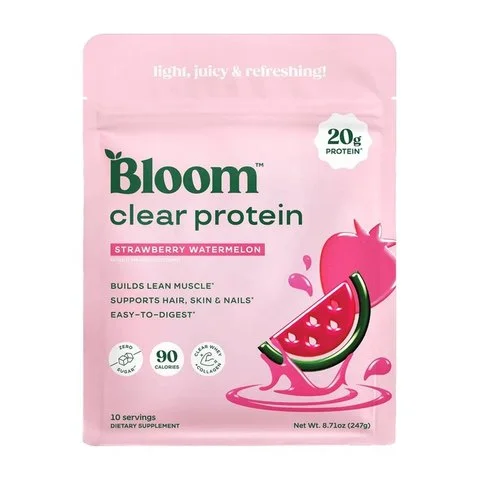
The last three places go to protein without a shake. Javvy's collagen creamer, stirred into coffee, is eighth. Two clear protein powders follow, with Arrae's Raspberry Yuzu in ninth and Bloom's Clear Protein in tenth. Consumption of each more than doubled in the quarter. Clear ready-to-drink protein shakes grew 34% in 2025, faster than any other protein format, according to SPINS. That makes a lot of sense to us, as a lighter drink is often much easier to get down than a thick, milky shake, especially on the tougher days.

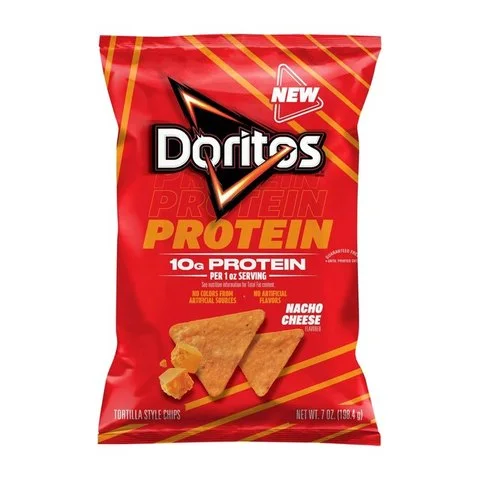
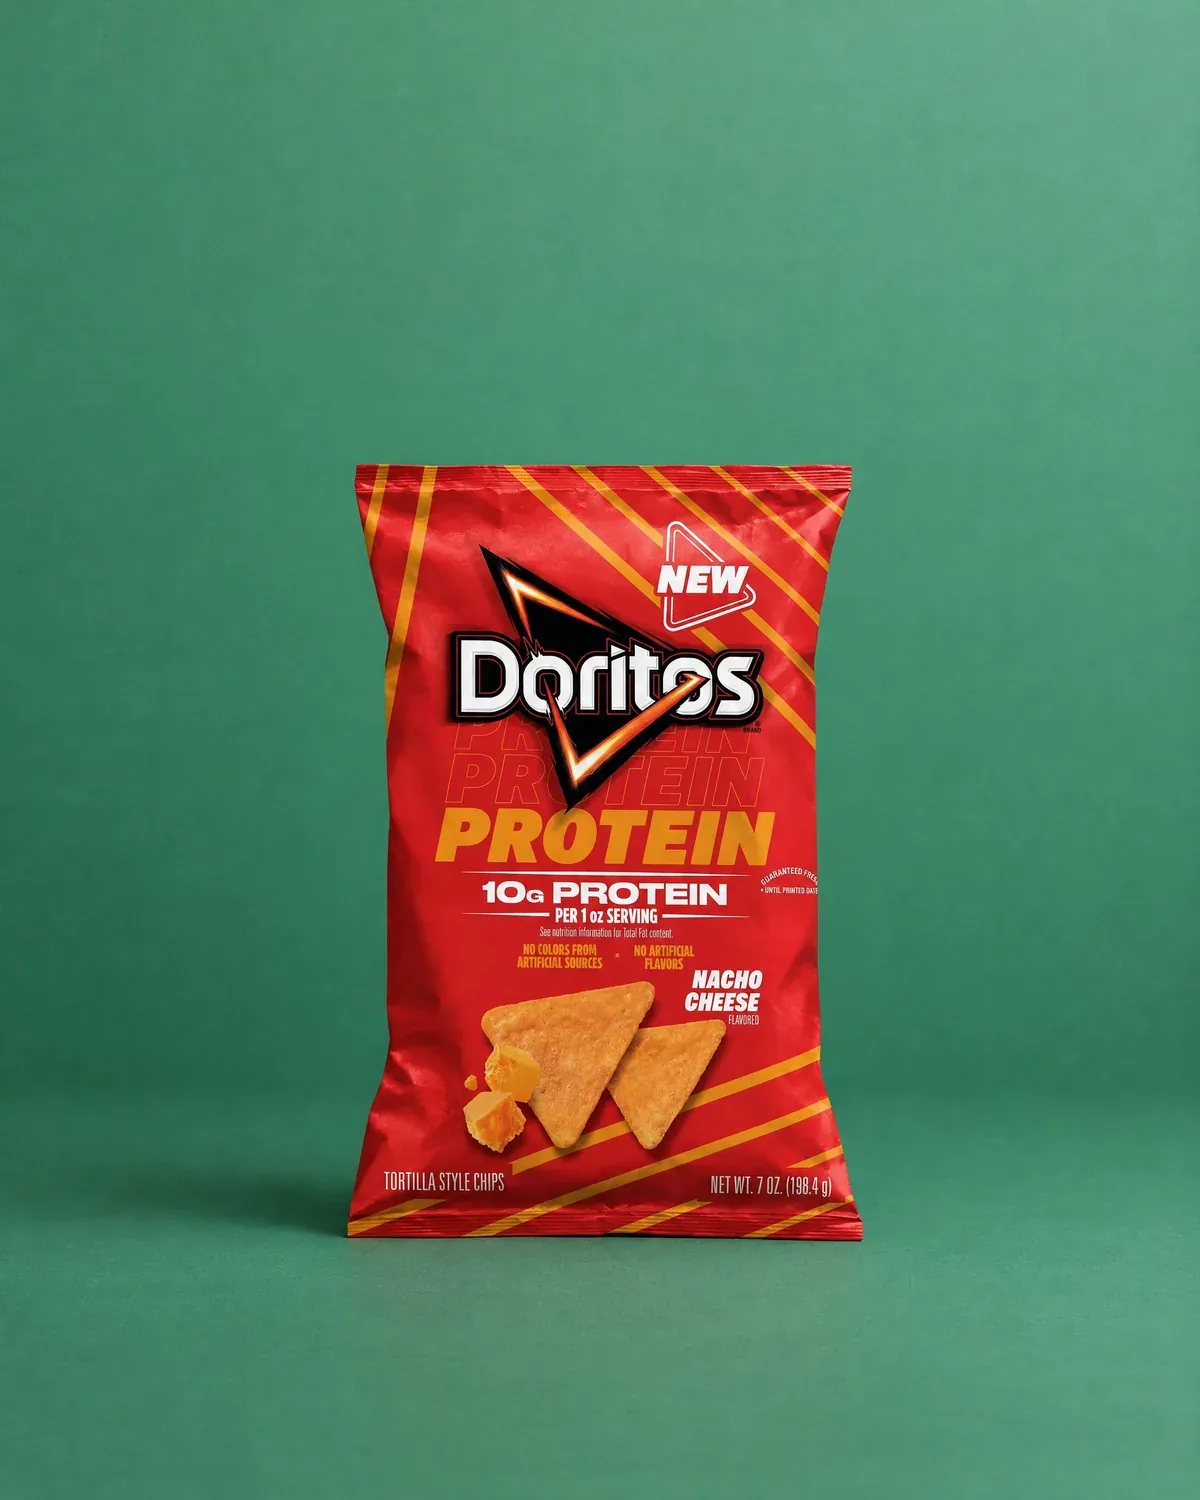
The Doritos Protein Nacho Cheese bag

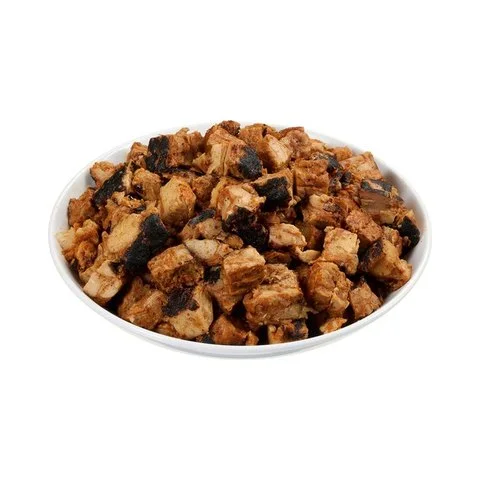
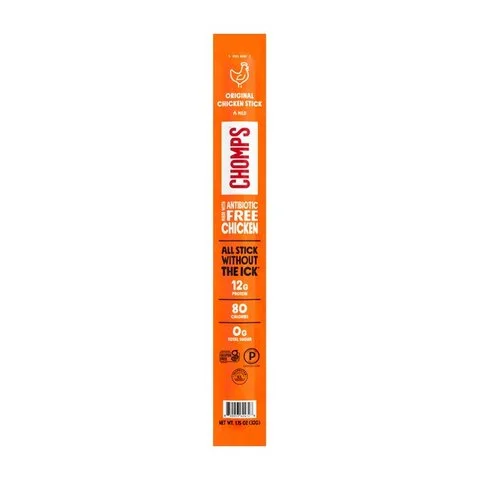
Savory protein makes it onto the list for the first time, with chips, chicken and roasted edamame all getting in this spring, and ready-to-eat chicken alone takes two places. Costco's Chargrilled Chipotle Chicken comes in second, having shown up in Costco delis early in the year before going viral on TikTok and Reddit, while Chomps' first chicken stick is seventh after reaching Target in April. They are the two most consumed meat products new to the MeAgain platform this year. In February, Fortune named meat snacks the clear winner of the GLP-1 shift. Protein that needs no cooking suits days when appetite is low and users get tired of the sweetness of bars and shakes.

Doritos Protein makes its debut in third place after PepsiCo put it on shelves in March with 10 grams of protein an ounce. It is the most consumed salty snack new to MeAgain this year, another winner of the growing savory protein trend. Beyond Doritos, PepsiCo is thinking a lot bigger, with its chief executive calling GLP-1s more of an opportunity than a threat and naming protein, fiber and smaller portions as the ways to respond.

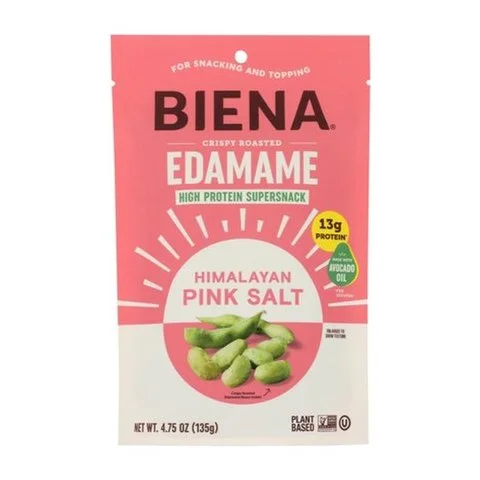
Biena's roasted edamame makes the list in fifth place as its consumption rose more than tenfold. Its founder named GLP-1 medications among the trends the crunchy, protein-rich snack fits when it launched in 2025.

+1,013%rise in consumption of Biena's roasted edamame among MeAgain members in Q2 2026

Top GLP-1 Brands

Q2 2026

Top GLP-1 brands are ranked based on product diversity & availability, consumer adoption, GLP-1 needs alignment, product ratings & reviews, and online conversations.

  1. 01Premier ProteinNo change
  2. 02FairlifeNo change
  3. 03Chobani1 place up
  4. 04Oikos1 place down
  5. 05QuestNo change
  6. 06Mission1 place up
  7. 07Vital Proteins3 places up
  8. 08Grüns3 places up
  9. 09BarebellsNo change
  10. 10Daisy3 places up
  1. 11Built5 places down
  2. 12Nurri4 places down
  3. 13Kodiak Cakes1 place up
  4. 14Chomps1 place up
  5. 15Kraft3 places up
  6. 16Great Value4 places down
  7. 17Sargento2 places up
  8. 18Quaker2 places down
  9. 19Trader Joe's2 places down
  10. 20Nature ValleyNew

Dropped out

  • Jimmy DeanLast quarter: 20
A range of Premier Protein shakes in several flavours

Premier Protein holds onto the top spot for another quarter, and our members still consume more of it than any other brand. Its shakes were even the biggest seller of Amazon's Prime Day in June, according to Numerator. Other brands have noticed, of course, with about 40 new ready-to-drink protein rivals in just 18 months.

Vital Proteins and Grüns each climbed three places this quarter. Vital Proteins, now seventh, is doing a lot more than collagen powder these days, rolling out a collagen sparkling water and adding a collagen and creatine blend in April. Grüns moved up to eighth as it kept spreading into more stores, going nationwide at Costco in late March and reaching Ulta in April.

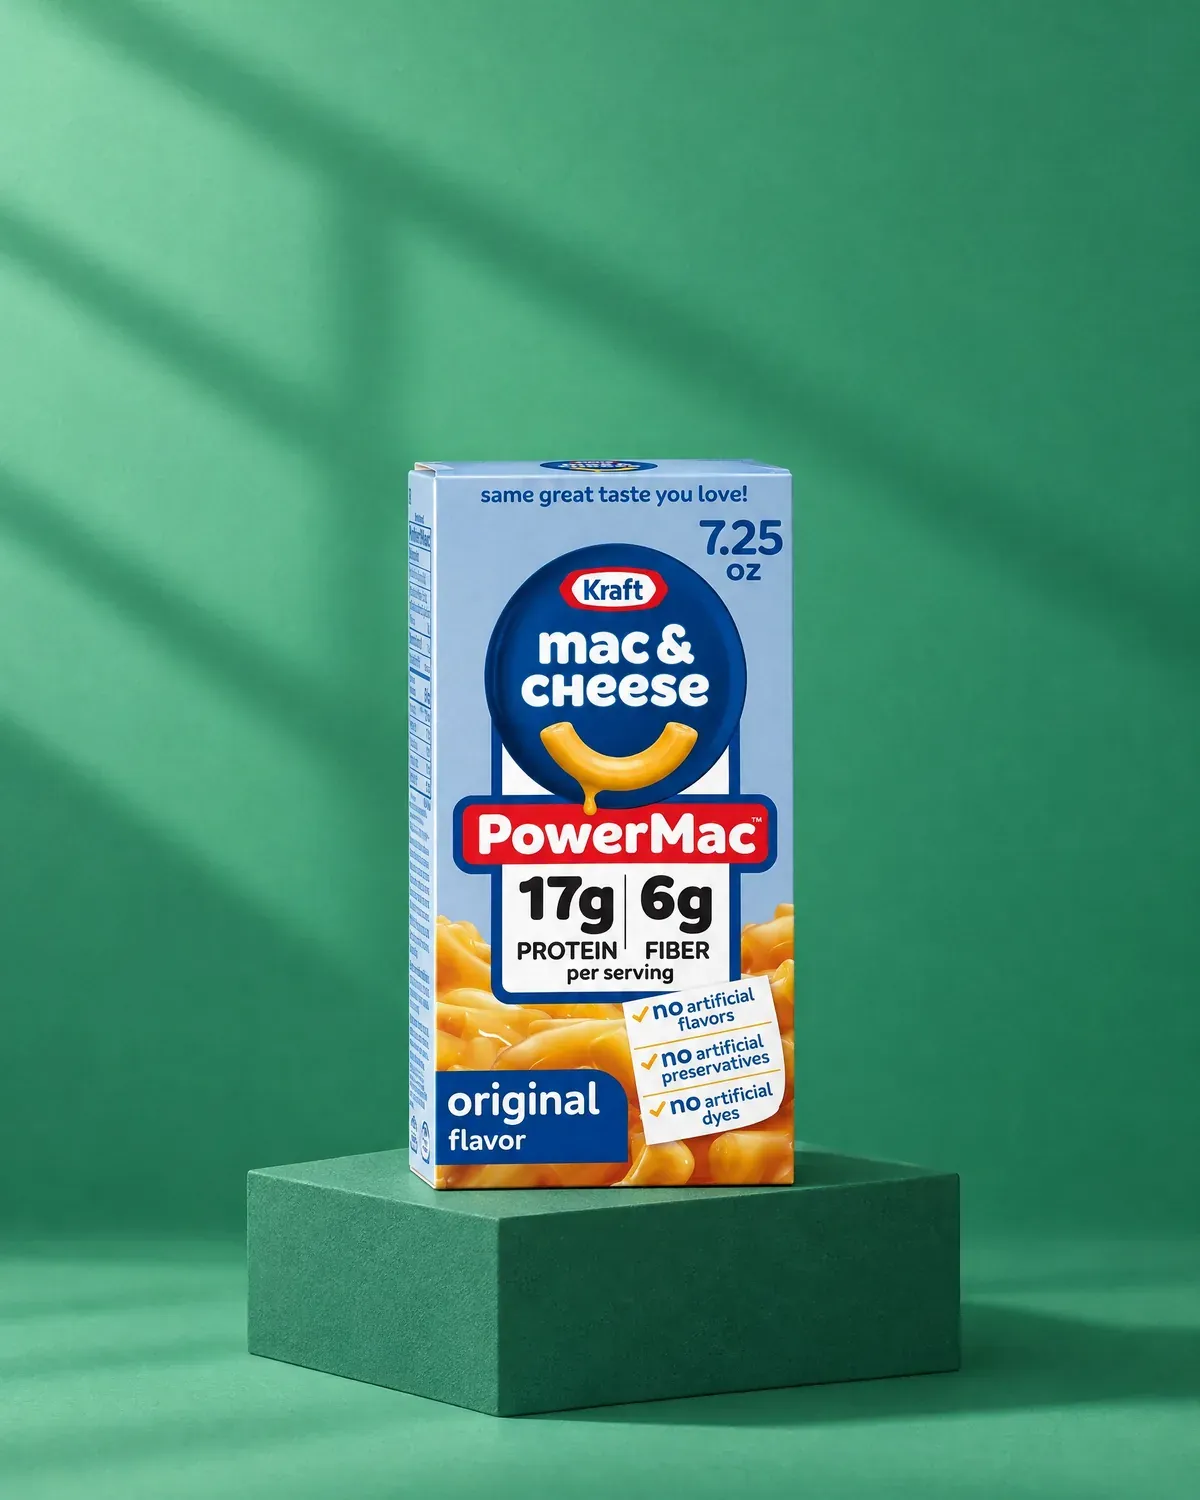
Kraft PowerMac mac and cheese, Grüns greens gummies and a Chomps chicken stick together

Kraft climbs three places to 15th as mentions of it in GLP-1 social posts rose 39%. PowerMac, a boxed mac and cheese with 17 grams of protein and 6 of fiber, reached shelves in April, and 35,000 retail accounts had taken it by early May. The launch was linked to healthier eating, partly due to GLP-1 drugs.

Nature Valley breaks into the list for the first time, in 20th place, after introducing soft-baked PB&J bars. Chomps and Sargento also moved up with new snacks: Chomps to 14th after its first chicken sticks came out in April, and Sargento to 17th with Mighty Bites snack kits that carry up to 14 grams of protein. Protein used to mean a bar or a shake, but now it is turning up in lunch kits and in the mac and cheese a lot of us grew up with.

+39%rise in mentions of Kraft in GLP-1 social posts in Q2 2026

This quarter, a lot of the climbing was done by brands putting protein into things people already buy, so we would not be surprised if the next big GLP-1 brand turns out to be one our members have known for years.

Previous editionMeAgain IndexQ1 2026Lilly Leads Meds, and Protein Leads Everything Else

The MeAgain Index

Press

index@meagain.com

How to cite

The MeAgain Index Q2 2026, MeAgain, meagain.com/index/q2-2026

All data aggregated and de-identified. Observational patterns from people who log in the MeAgain app, not causal claims. © Dots Future Technologies, Inc. 2026

About MeAgain: MeAgain is the largest neutral GLP-1 platform and has helped more than a million people start their GLP-1 journey. It uses its unique position in the market to give this independent, third-party view of the GLP-1 ecosystem. MeAgain is not affiliated with, sponsored by or endorsed by any brand, product or medicine named here. All brand names, product names and trademarks belong to their owners and are used only to identify them. Product images are illustrations.

Methodology

The MeAgain Index

Three GLP-1 lists, every quarter

  1. Top 10

    Leading GLP-1 Meds

    The leading GLP-1 meds are evaluated across pricing, insurance coverage, adoption, adherence, real-world weight loss outcomes, quality-of-life improvements, and new research.

  2. Top 10

    Trending GLP-1 Products

    The fastest-growing and most culturally relevant products for GLP-1 users in the quarter, based on new launches, real-world adoption, social media, AI search and other online conversations.

  3. Top 20

    Top GLP-1 Brands

    Top GLP-1 brands are ranked based on product diversity & availability, consumer adoption, GLP-1 needs alignment, product ratings & reviews, and online conversations.

How the MeAgain Index is calculated

The MeAgain Index methodology is built on three dimensions: Access, Use and Impact.

Access

01Is it easy to find?
Visibility in web search and AI assistants, sale through proper channels rather than the black market, and a wide range of GLP-1-friendly options.
02Is it easy to understand?
Clear labeling that shows it suits GLP-1 users, such as a high-protein claim. For medications, studies and other information published in terms the everyday consumer can understand and use for decision-making.
03Is it easy to buy?
Price, insurance coverage where it applies, how many pharmacies, stores and online shops sell it, and whether buying it needs a paid membership.

Use

01Do people consider using it?
Interest before people start, measured through social media conversation, AI search and general search volume.
02Do people start using it?
How many people bring a brand or product into their routine or start a medication, from real-world data on the MeAgain platform and third-party sources.
03Do people keep using it?
How many keep using or taking it, from repeat logging on the MeAgain platform and third-party data such as prescription refills.

Impact

01Does it improve health?
Health results such as weight loss among the people using it, alongside published third-party studies.
02Does it improve daily life?
Side effects, tone and sentiment from users on the MeAgain platform, case studies and third-party studies of wider effects, such as drinking less alcohol.
03Do people recommend it?
Posts and comments on Reddit, TikTok, Instagram and YouTube, plus ratings, reviews and polls on the MeAgain platform.

How to read the rankings

+3
Places up since last quarter
−2
Places down since last quarter
–
Same place as last quarter
New
New to the list this quarter
Dropped out
On last quarter's list, not on this one
Seasonal
A seasonal product

Unique combination of proprietary data and external sources

Depending on the signal, the MeAgain Index draws on proprietary data from hundreds of thousands of members on the MeAgain platform and tens of millions of data points. This is connected with external data sources and custom-built in-house tools that track the wider GLP-1 market, to give the most comprehensive view of GLP-1 use available. Figures from the MeAgain platform are adjusted for the growth of our member base.

How often the MeAgain Index is published

The MeAgain Index is published every quarter. Each dimension is scored and weighted using a proprietary model built by the MeAgain data team. The exact formula is not disclosed.

A living methodology

We expect the MeAgain Index to keep evolving as the MeAgain platform grows and GLP-1 treatment continues to change, and we will add new data sources once we are confident they are reliable enough to include. All figures are aggregated and anonymized, and we never show any individual's data.

For more information about the MeAgain Index please contact index@meagain.com